THE PRESENTATION MATERIALS
Published on October 14, 2026
Bank of America 3Q26 Financial Results October 14, 2026
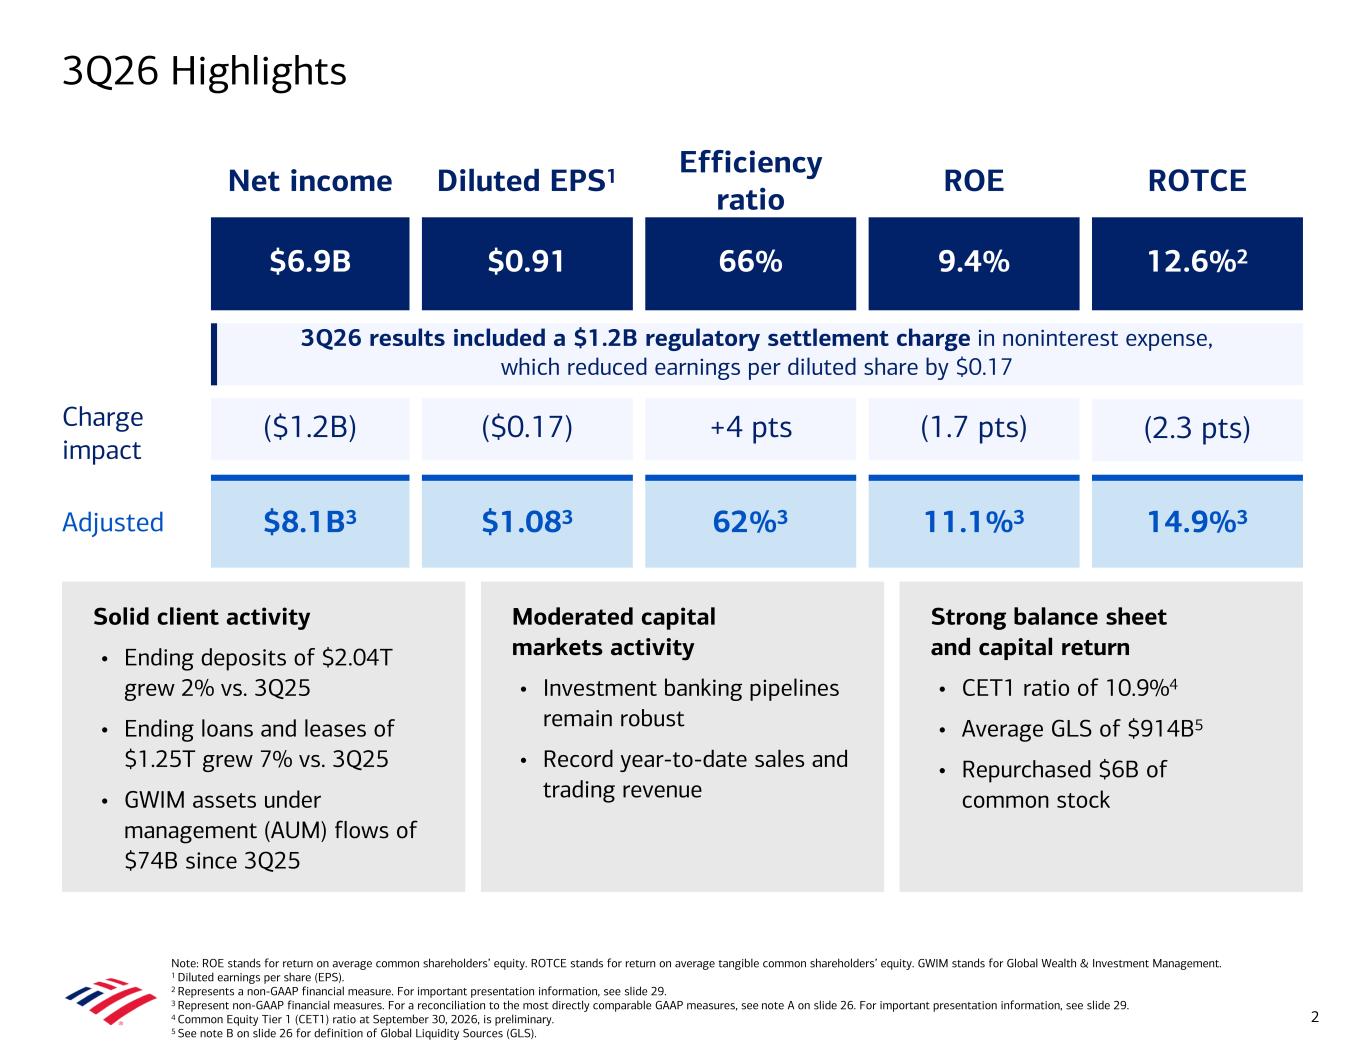
Solid client activity • Ending deposits of $2.04T grew 2% vs. 3Q25 • Ending loans and leases of $1.25T grew 7% vs. 3Q25 • GWIM assets under management (AUM) flows of $74B since 3Q25 Note: ROE stands for return on average common shareholders’ equity. ROTCE stands for return on average tangible common shareholders’ equity. GWIM stands for Global Wealth & Investment Management. 1 Diluted earnings per share (EPS). 2 Represents a non-GAAP financial measure. For important presentation information, see slide 29. 3 Represent non-GAAP financial measures. For a reconciliation to the most directly comparable GAAP measures, see note A on slide 26. For important presentation information, see slide 29. 4 Common Equity Tier 1 (CET1) ratio at September 30, 2026, is preliminary. 5 See note B on slide 26 for definition of Global Liquidity Sources (GLS). 3Q26 Highlights 2 Net income Diluted EPS1 Efficiency ratio ROE ROTCE $8.1B3 $1.083 62%3 11.1%3 14.9%3 ($1.2B) ($0.17) +4 pts (1.7 pts) (2.3 pts) 3Q26 results included a $1.2B regulatory settlement charge in noninterest expense, which reduced earnings per diluted share by $0.17 $6.9B $0.91 66% 9.4% 12.6%2 Adjusted Moderated capital markets activity • Investment banking pipelines remain robust • Record year-to-date sales and trading revenue Strong balance sheet and capital return • CET1 ratio of 10.9%4 • Average GLS of $914B5 • Repurchased $6B of common stock Charge impact
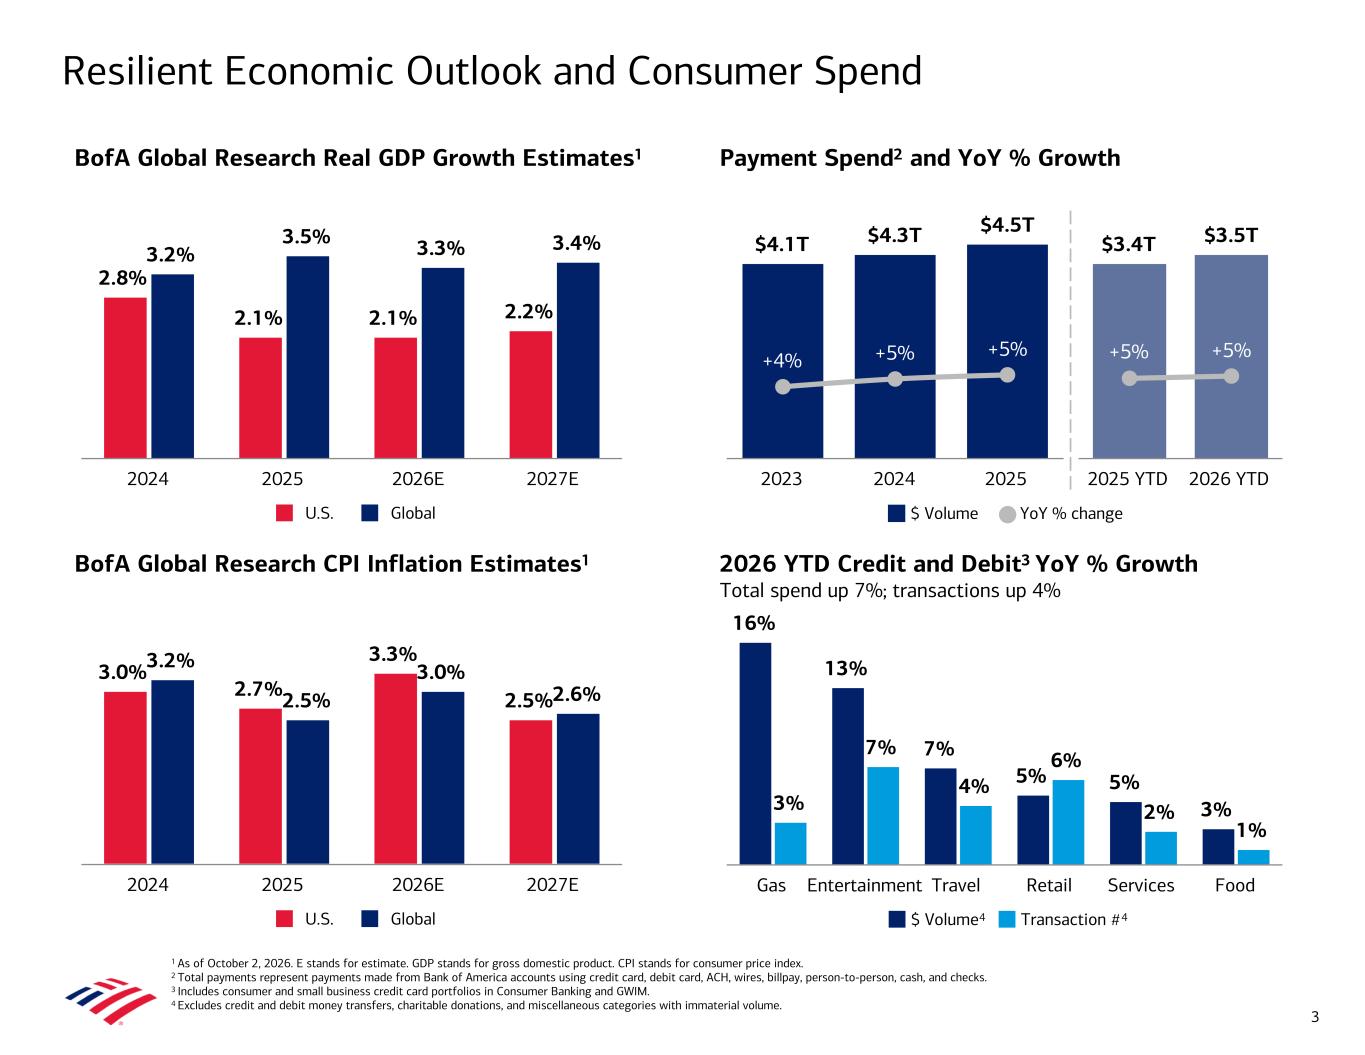
Resilient Economic Outlook and Consumer Spend BofA Global Research CPI Inflation Estimates1 3 2026 YTD Credit and Debit3 YoY % Growth Total spend up 7%; transactions up 4% 16% 13% 7% 5% 5% 3%3% 7% 4% 6% 2% 1% $ Volume Transaction # Gas Entertainment Travel Retail Services Food Payment Spend2 and YoY % Growth $4.1T $4.3T $4.5T +4% +5% +5% 2023 2024 2025 BofA Global Research Real GDP Growth Estimates1 1 As of October 2, 2026. E stands for estimate. GDP stands for gross domestic product. CPI stands for consumer price index. 2 Total payments represent payments made from Bank of America accounts using credit card, debit card, ACH, wires, billpay, person-to-person, cash, and checks. 3 Includes consumer and small business credit card portfolios in Consumer Banking and GWIM. 4 Excludes credit and debit money transfers, charitable donations, and miscellaneous categories with immaterial volume. 4 4 2.8% 2.1% 2.1% 2.2% 3.2% 3.5% 3.3% 3.4% U.S. Global 2024 2025 2026E 2027E 3.0% 2.7% 3.3% 2.5% 3.2% 2.5% 3.0% 2.6% U.S. Global 2024 2025 2026E 2027E $3.4T $3.5T +5% +5% 2025 YTD 2026 YTD $ Volume YoY % change
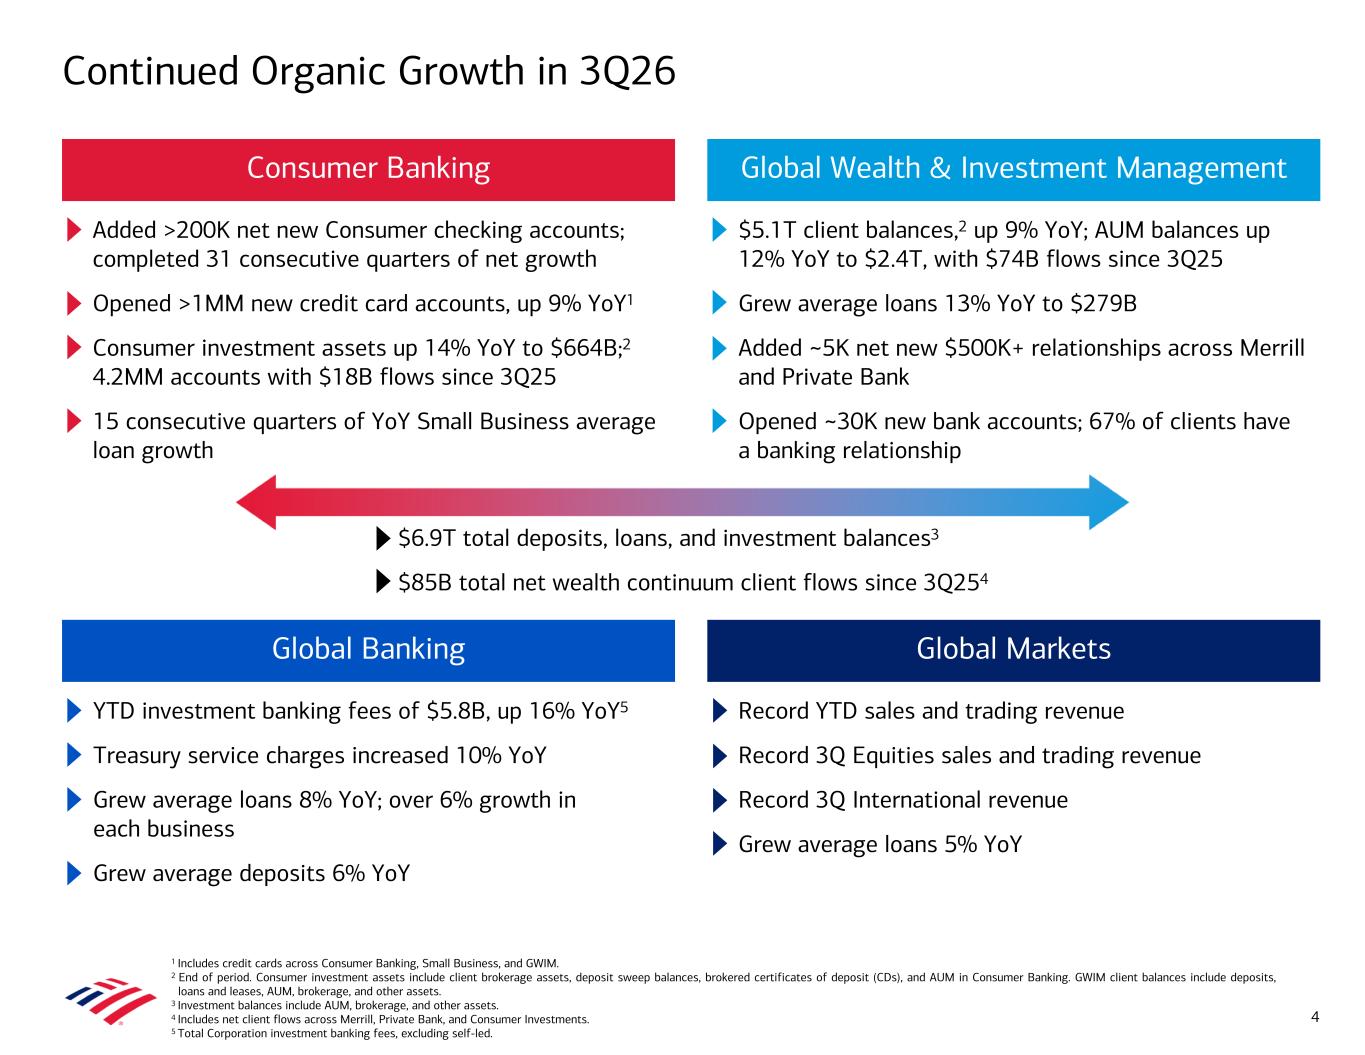
Record YTD sales and trading revenue Record 3Q Equities sales and trading revenue Record 3Q International revenue Grew average loans 5% YoY Added >200K net new Consumer checking accounts; completed 31 consecutive quarters of net growth Opened >1MM new credit card accounts, up 9% YoY1 Consumer investment assets up 14% YoY to $664B;2 4.2MM accounts with $18B flows since 3Q25 15 consecutive quarters of YoY Small Business average loan growth 1 Includes credit cards across Consumer Banking, Small Business, and GWIM. 2 End of period. Consumer investment assets include client brokerage assets, deposit sweep balances, brokered certificates of deposit (CDs), and AUM in Consumer Banking. GWIM client balances include deposits, loans and leases, AUM, brokerage, and other assets. 3 Investment balances include AUM, brokerage, and other assets. 4 Includes net client flows across Merrill, Private Bank, and Consumer Investments. 5 Total Corporation investment banking fees, excluding self-led. Continued Organic Growth in 3Q26 4 Consumer Banking Global Wealth & Investment Management Global Banking Global Markets $6.9T total deposits, loans, and investment balances3 $85B total net wealth continuum client flows since 3Q254 $5.1T client balances,2 up 9% YoY; AUM balances up 12% YoY to $2.4T, with $74B flows since 3Q25 Grew average loans 13% YoY to $279B Added ~5K net new $500K+ relationships across Merrill and Private Bank Opened ~30K new bank accounts; 67% of clients have a banking relationship YTD investment banking fees of $5.8B, up 16% YoY5 Treasury service charges increased 10% YoY Grew average loans 8% YoY; over 6% growth in each business Grew average deposits 6% YoY
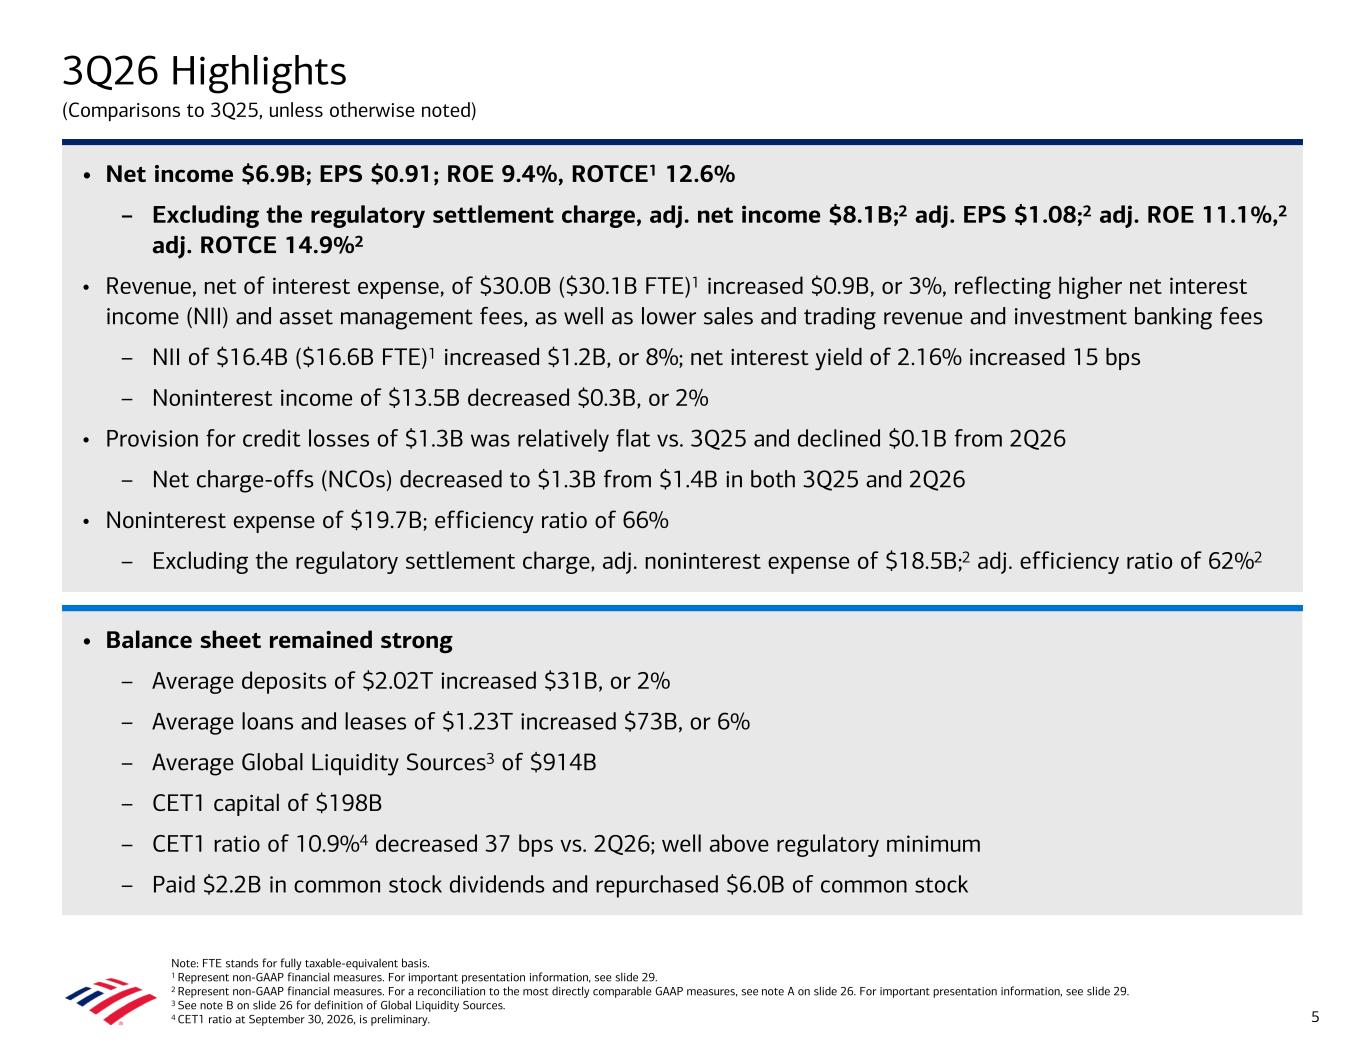
• Balance sheet remained strong – Average deposits of $2.02T increased $31B, or 2% – Average loans and leases of $1.23T increased $73B, or 6% – Average Global Liquidity Sources3 of $914B – CET1 capital of $198B – CET1 ratio of 10.9%4 decreased 37 bps vs. 2Q26; well above regulatory minimum – Paid $2.2B in common stock dividends and repurchased $6.0B of common stock • Net income $6.9B; EPS $0.91; ROE 9.4%, ROTCE1 12.6% – Excluding the regulatory settlement charge, adj. net income $8.1B;2 adj. EPS $1.08;2 adj. ROE 11.1%,2 adj. ROTCE 14.9%2 • Revenue, net of interest expense, of $30.0B ($30.1B FTE)1 increased $0.9B, or 3%, reflecting higher net interest income (NII) and asset management fees, as well as lower sales and trading revenue and investment banking fees – NII of $16.4B ($16.6B FTE)1 increased $1.2B, or 8%; net interest yield of 2.16% increased 15 bps – Noninterest income of $13.5B decreased $0.3B, or 2% • Provision for credit losses of $1.3B was relatively flat vs. 3Q25 and declined $0.1B from 2Q26 – Net charge-offs (NCOs) decreased to $1.3B from $1.4B in both 3Q25 and 2Q26 • Noninterest expense of $19.7B; efficiency ratio of 66% – Excluding the regulatory settlement charge, adj. noninterest expense of $18.5B;2 adj. efficiency ratio of 62%2 Note: FTE stands for fully taxable-equivalent basis. 1 Represent non-GAAP financial measures. For important presentation information, see slide 29. 2 Represent non-GAAP financial measures. For a reconciliation to the most directly comparable GAAP measures, see note A on slide 26. For important presentation information, see slide 29. 3 See note B on slide 26 for definition of Global Liquidity Sources. 4 CET1 ratio at September 30, 2026, is preliminary. 3Q26 Highlights (Comparisons to 3Q25, unless otherwise noted) 5
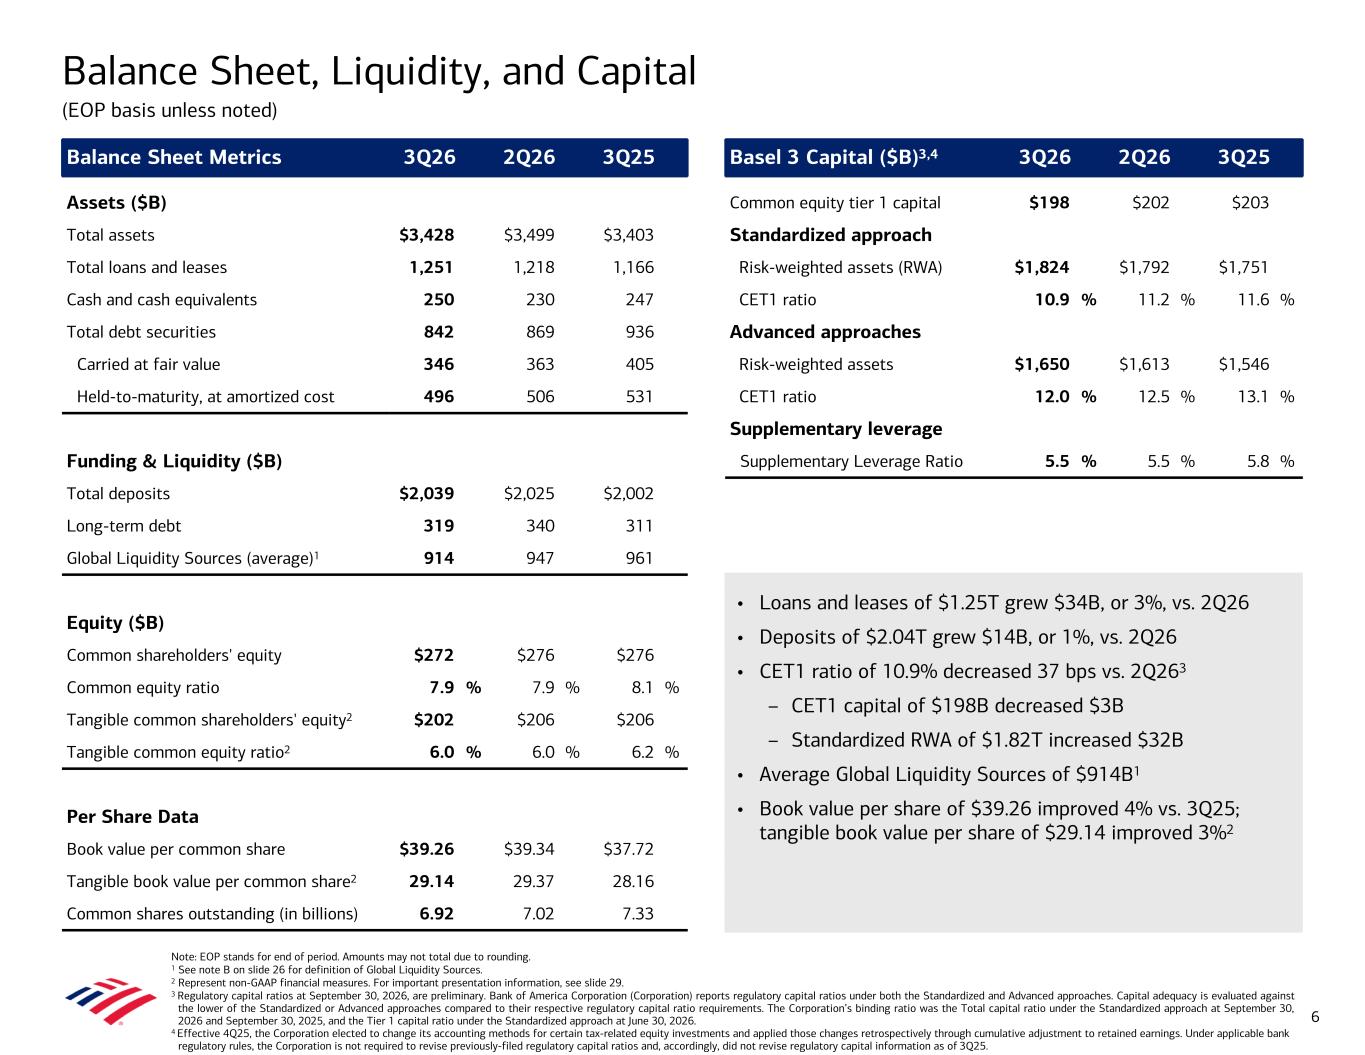
Balance Sheet Metrics 3Q26 2Q26 3Q25 Basel 3 Capital ($B)3,4 3Q26 2Q26 3Q25 Assets ($B) Common equity tier 1 capital $198 $202 $203 Total assets $3,428 $3,499 $3,403 Standardized approach Total loans and leases 1,251 1,218 1,166 Risk-weighted assets (RWA) $1,824 $1,792 $1,751 Cash and cash equivalents 250 230 247 CET1 ratio 10.9 % 11.2 % 11.6 % Total debt securities 842 869 936 Advanced approaches Carried at fair value 346 363 405 Risk-weighted assets $1,650 $1,613 $1,546 Held-to-maturity, at amortized cost 496 506 531 CET1 ratio 12.0 % 12.5 % 13.1 % Supplementary leverage Funding & Liquidity ($B) Supplementary Leverage Ratio 5.5 % 5.5 % 5.8 % Total deposits $2,039 $2,025 $2,002 Long-term debt 319 340 311 Global Liquidity Sources (average)1 914 947 961 Equity ($B) Common shareholders' equity $272 $276 $276 Common equity ratio 7.9 % 7.9 % 8.1 % Tangible common shareholders' equity2 $202 $206 $206 Tangible common equity ratio2 6.0 % 6.0 % 6.2 % Per Share Data Book value per common share $39.26 $39.34 $37.72 Tangible book value per common share2 29.14 29.37 28.16 Common shares outstanding (in billions) 6.92 7.02 7.33 Balance Sheet, Liquidity, and Capital (EOP basis unless noted) 6 • Loans and leases of $1.25T grew $34B, or 3%, vs. 2Q26 • Deposits of $2.04T grew $14B, or 1%, vs. 2Q26 • CET1 ratio of 10.9% decreased 37 bps vs. 2Q263 – CET1 capital of $198B decreased $3B – Standardized RWA of $1.82T increased $32B • Average Global Liquidity Sources of $914B1 • Book value per share of $39.26 improved 4% vs. 3Q25; tangible book value per share of $29.14 improved 3%2 Note: EOP stands for end of period. Amounts may not total due to rounding. 1 See note B on slide 26 for definition of Global Liquidity Sources. 2 Represent non-GAAP financial measures. For important presentation information, see slide 29. 3 Regulatory capital ratios at September 30, 2026, are preliminary. Bank of America Corporation (Corporation) reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was the Total capital ratio under the Standardized approach at September 30, 2026 and September 30, 2025, and the Tier 1 capital ratio under the Standardized approach at June 30, 2026. 4 Effective 4Q25, the Corporation elected to change its accounting methods for certain tax-related equity investments and applied those changes retrospectively through cumulative adjustment to retained earnings. Under applicable bank regulatory rules, the Corporation is not required to revise previously-filed regulatory capital ratios and, accordingly, did not revise regulatory capital information as of 3Q25.
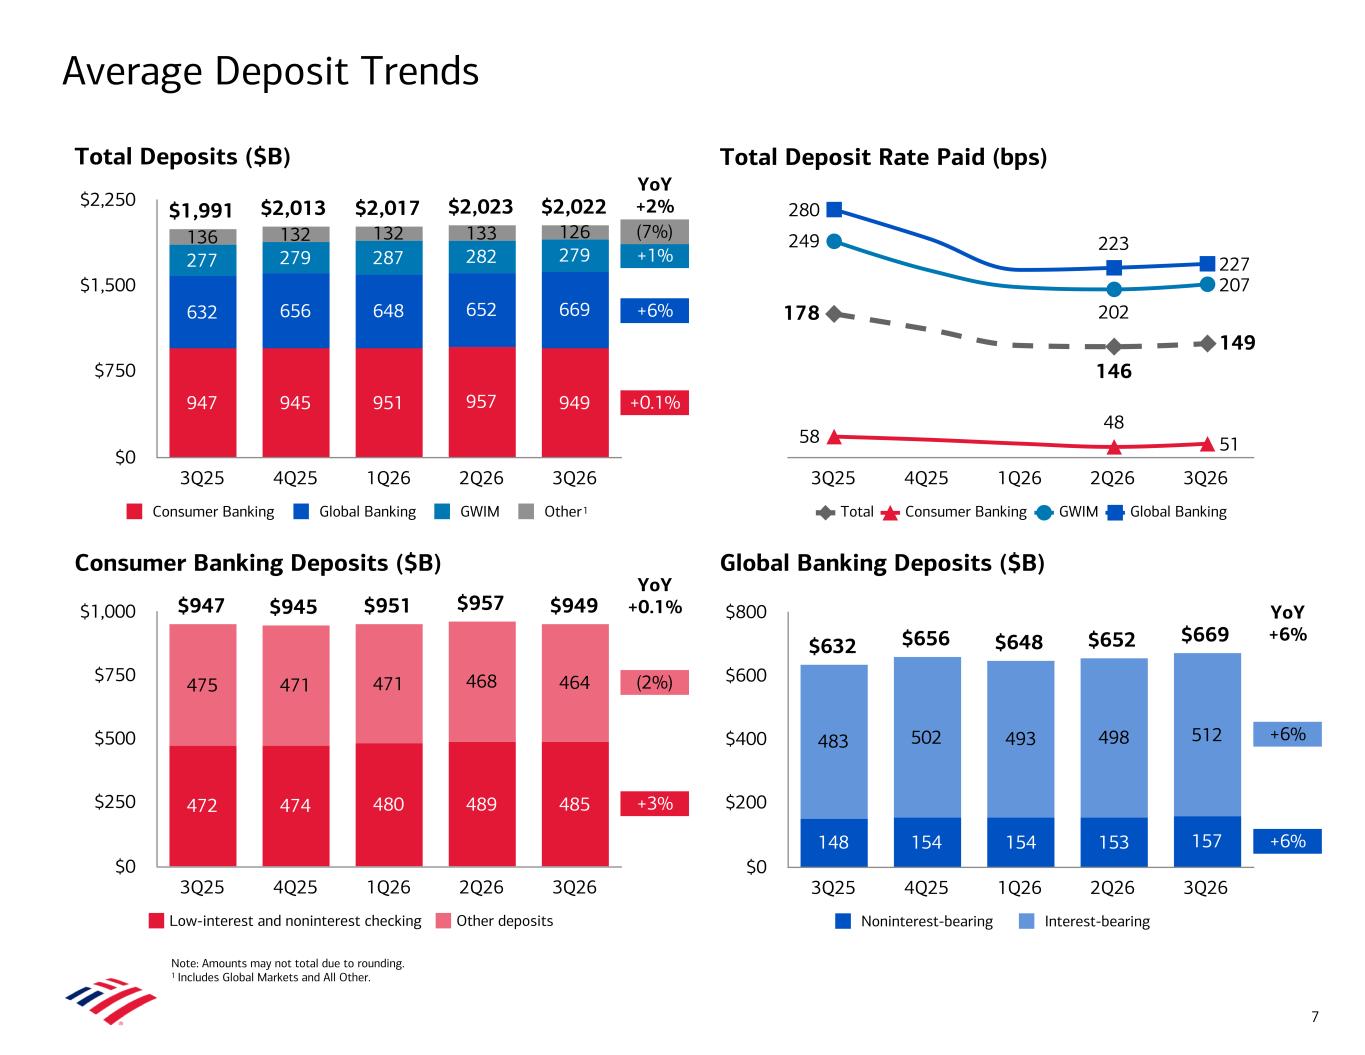
$947 $945 $951 $957 $949 472 474 480 489 485 475 471 471 468 464 Low-interest and noninterest checking Other deposits 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $250 $500 $750 $1,000 +3% (2%) Average Deposit Trends YoY +2% Note: Amounts may not total due to rounding. 1 Includes Global Markets and All Other. YoY +0.1% Global Banking Deposits ($B) Consumer Banking Deposits ($B) Total Deposit Rate Paid (bps)Total Deposits ($B) 178 146 149 58 48 51 249 202 207 280 223 227 Total Consumer Banking GWIM Global Banking 3Q25 4Q25 1Q26 2Q26 3Q26 7 $632 $656 $648 $652 $669 148 154 154 153 157 483 502 493 498 512 Noninterest-bearing Interest-bearing 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $200 $400 $600 $800 $1,991 $2,013 $2,017 $2,023 $2,022 947 945 951 957 949 632 656 648 652 669 277 279 287 282 279 136 132 132 133 126 Consumer Banking Global Banking GWIM Other 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $750 $1,500 $2,250 +0.1% +1% +6% +6% +6% YoY +6% 1 (7%)
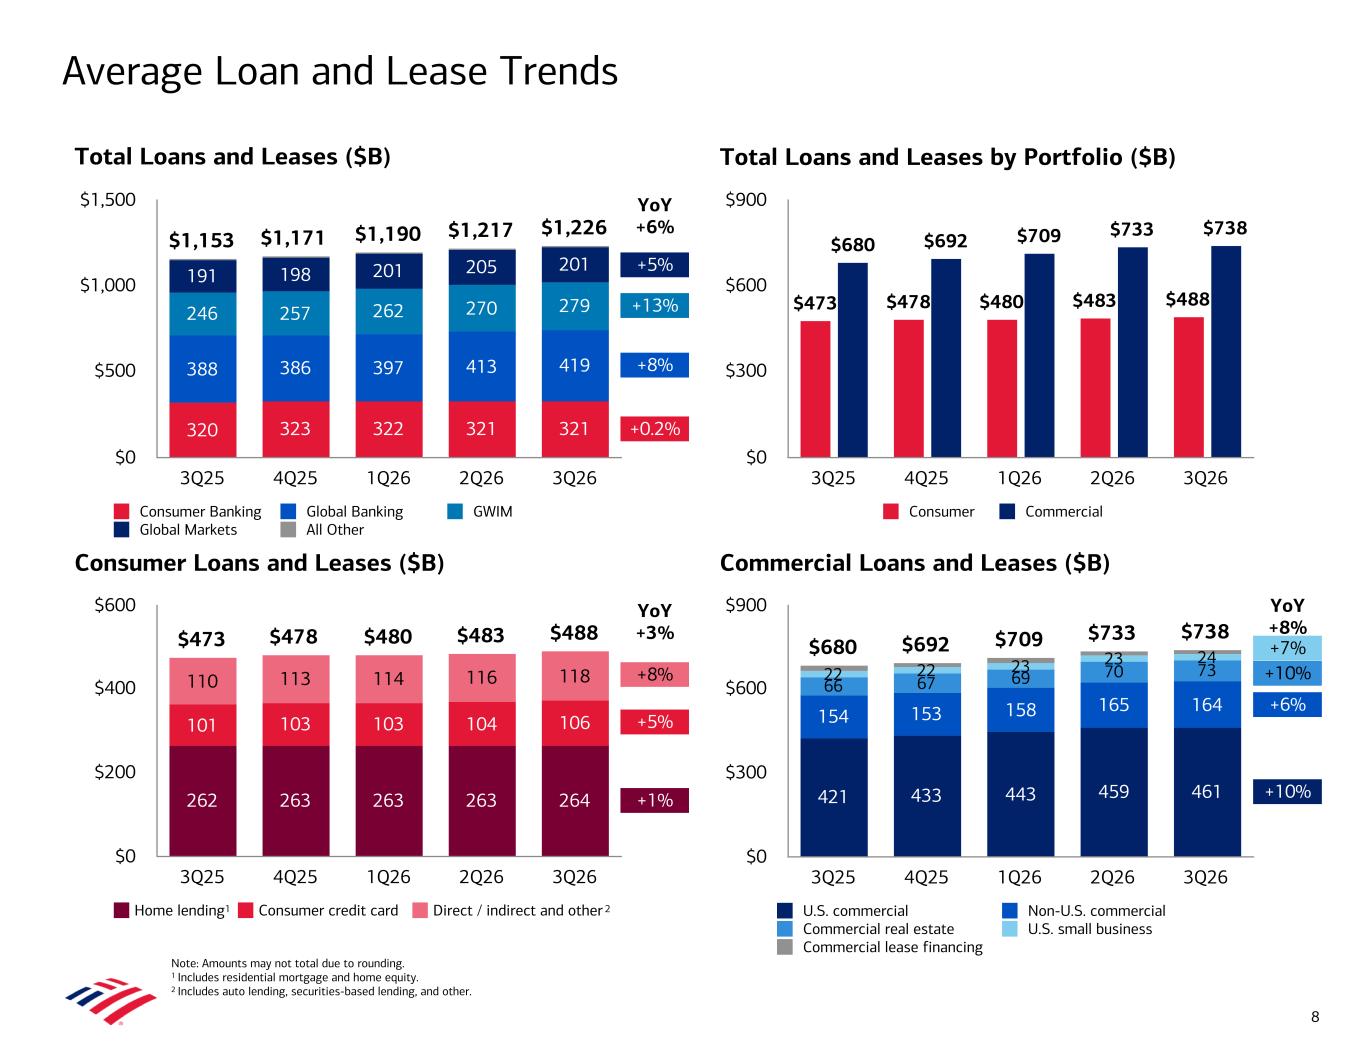
$473 $478 $480 $483 $488 262 263 263 263 264 101 103 103 104 106 110 113 114 116 118 Home lending Consumer credit card Direct / indirect and other 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $200 $400 $600 +1% +5% +8% Average Loan and Lease Trends YoY +6% YoY +3% Note: Amounts may not total due to rounding. 1 Includes residential mortgage and home equity. 2 Includes auto lending, securities-based lending, and other. Commercial Loans and Leases ($B) Consumer Loans and Leases ($B) Total Loans and Leases by Portfolio ($B)Total Loans and Leases ($B) $473 $478 $480 $483 $488 $680 $692 $709 $733 $738 Consumer Commercial 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $300 $600 $900 8 $680 $692 $709 $733 $738 421 433 443 459 461 154 153 158 165 164 66 67 69 70 7322 22 23 23 24 U.S. commercial Non-U.S. commercial Commercial real estate U.S. small business Commercial lease financing 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $300 $600 $900 $1,153 $1,171 $1,190 $1,217 $1,226 320 323 322 321 321 388 386 397 413 419 246 257 262 270 279 191 198 201 205 201 Consumer Banking Global Banking GWIM Global Markets All Other 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $500 $1,000 $1,500 +0.2% +13% +8% +5% 1 +10% +6% +10% YoY +8% +7% 2
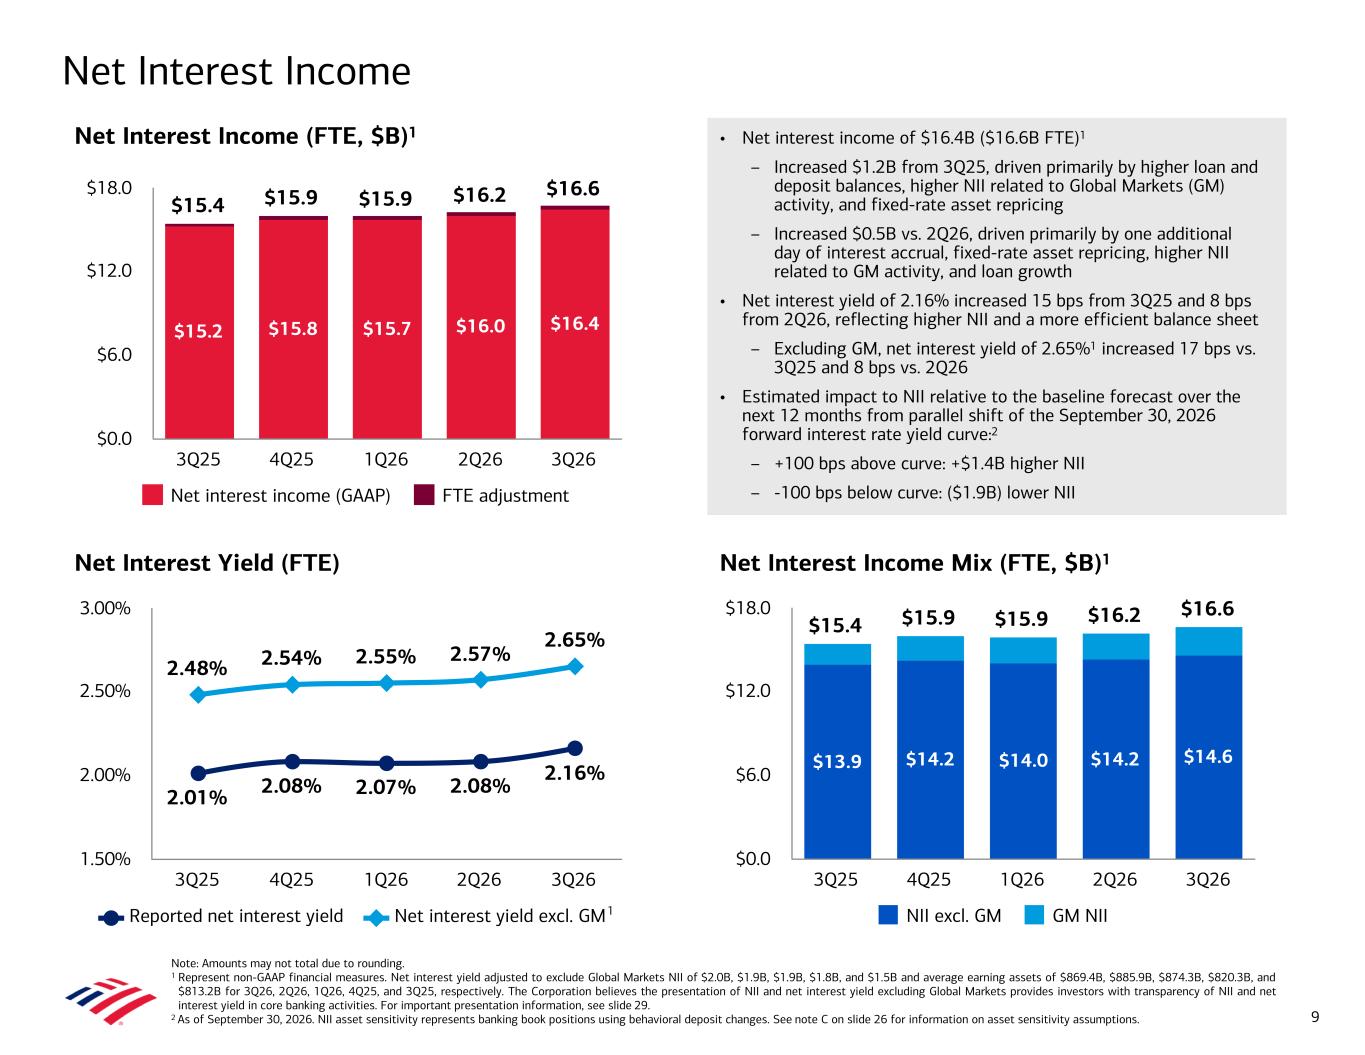
• Net interest income of $16.4B ($16.6B FTE)1 – Increased $1.2B from 3Q25, driven primarily by higher loan and deposit balances, higher NII related to Global Markets (GM) activity, and fixed-rate asset repricing – Increased $0.5B vs. 2Q26, driven primarily by one additional day of interest accrual, fixed-rate asset repricing, higher NII related to GM activity, and loan growth • Net interest yield of 2.16% increased 15 bps from 3Q25 and 8 bps from 2Q26, reflecting higher NII and a more efficient balance sheet – Excluding GM, net interest yield of 2.65%1 increased 17 bps vs. 3Q25 and 8 bps vs. 2Q26 • Estimated impact to NII relative to the baseline forecast over the next 12 months from parallel shift of the September 30, 2026 forward interest rate yield curve:2 – +100 bps above curve: +$1.4B higher NII – -100 bps below curve: ($1.9B) lower NII Net Interest Income (FTE, $B)1 Net Interest Income Note: Amounts may not total due to rounding. 1 Represent non-GAAP financial measures. Net interest yield adjusted to exclude Global Markets NII of $2.0B, $1.9B, $1.9B, $1.8B, and $1.5B and average earning assets of $869.4B, $885.9B, $874.3B, $820.3B, and $813.2B for 3Q26, 2Q26, 1Q26, 4Q25, and 3Q25, respectively. The Corporation believes the presentation of NII and net interest yield excluding Global Markets provides investors with transparency of NII and net interest yield in core banking activities. For important presentation information, see slide 29. 2 As of September 30, 2026. NII asset sensitivity represents banking book positions using behavioral deposit changes. See note C on slide 26 for information on asset sensitivity assumptions. Net Interest Yield (FTE) 2.01% 2.08% 2.07% 2.08% 2.16% 2.48% 2.54% 2.55% 2.57% 2.65% Reported net interest yield Net interest yield excl. GM 3Q25 4Q25 1Q26 2Q26 3Q26 1.50% 2.00% 2.50% 3.00% $15.4 $15.9 $15.9 $16.2 $16.6 $15.2 $15.8 $15.7 $16.0 $16.4 Net interest income (GAAP) FTE adjustment 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $6.0 $12.0 $18.0 9 Net Interest Income Mix (FTE, $B)1 $15.4 $15.9 $15.9 $16.2 $16.6 $13.9 $14.2 $14.0 $14.2 $14.6 NII excl. GM GM NII 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $6.0 $12.0 $18.0 1
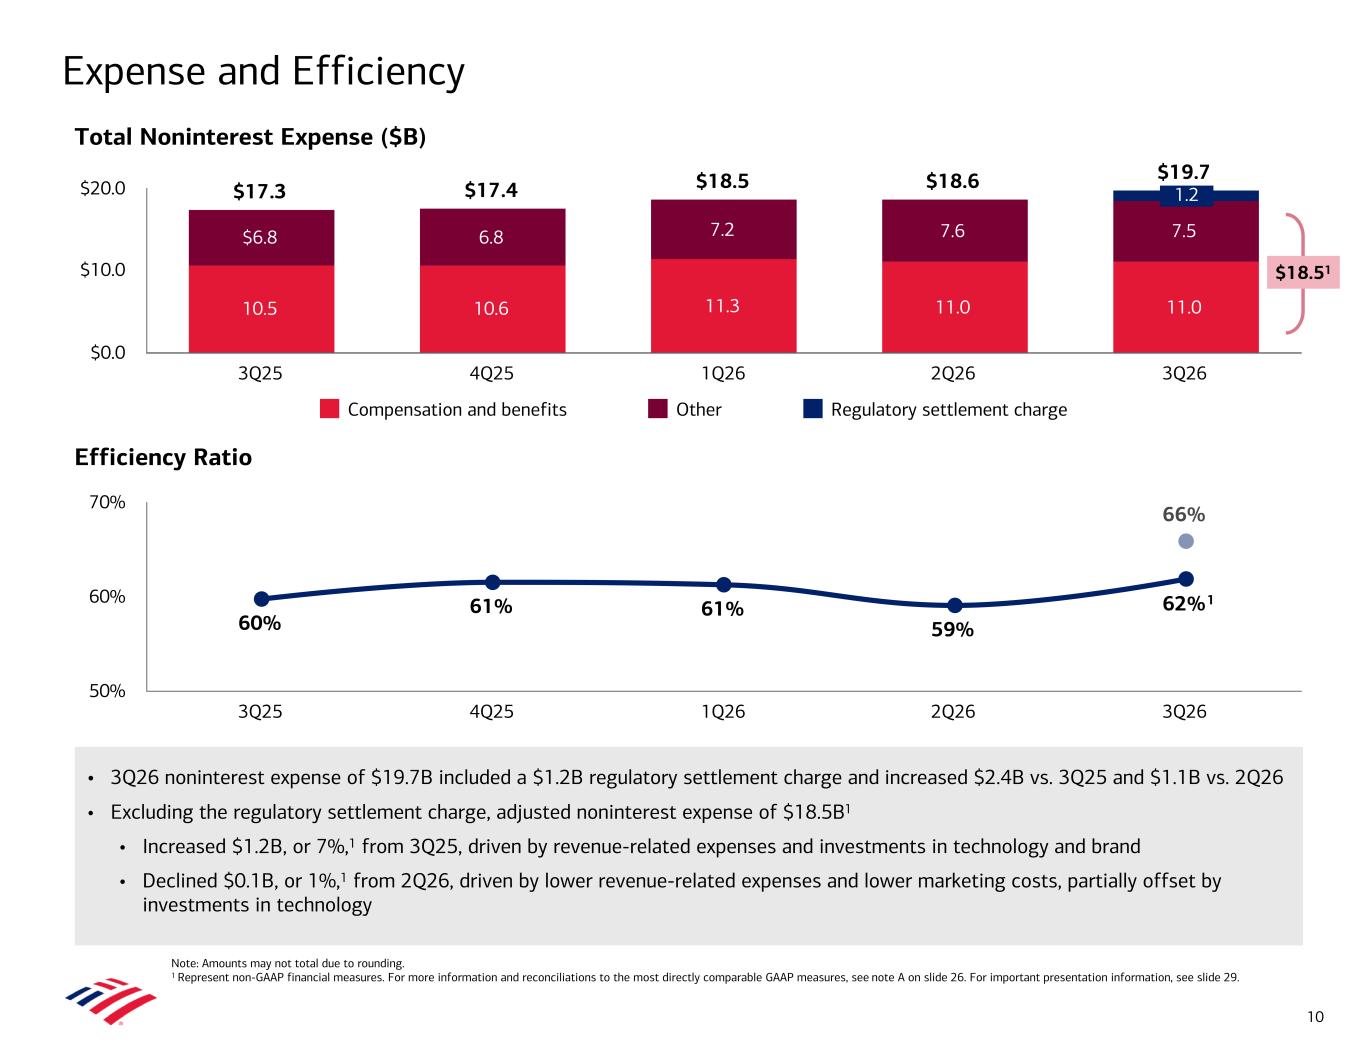
• 3Q26 noninterest expense of $19.7B included a $1.2B regulatory settlement charge and increased $2.4B vs. 3Q25 and $1.1B vs. 2Q26 • Excluding the regulatory settlement charge, adjusted noninterest expense of $18.5B1 • Increased $1.2B, or 7%,1 from 3Q25, driven by revenue-related expenses and investments in technology and brand • Declined $0.1B, or 1%,1 from 2Q26, driven by lower revenue-related expenses and lower marketing costs, partially offset by investments in technology $17.3 $17.4 $18.5 $18.6 $19.7 10.5 10.6 11.3 11.0 11.0 $6.8 6.8 7.2 7.6 7.5 Compensation and benefits Other Regulatory settlement charge 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $10.0 $20.0 60% 61% 61% 59% 62% 66% 3Q25 4Q25 1Q26 2Q26 3Q26 50% 60% 70% Total Noninterest Expense ($B) Efficiency Ratio Expense and Efficiency 10 Note: Amounts may not total due to rounding. 1 Represent non-GAAP financial measures. For more information and reconciliations to the most directly comparable GAAP measures, see note A on slide 26. For important presentation information, see slide 29. 1.2 $18.51 1
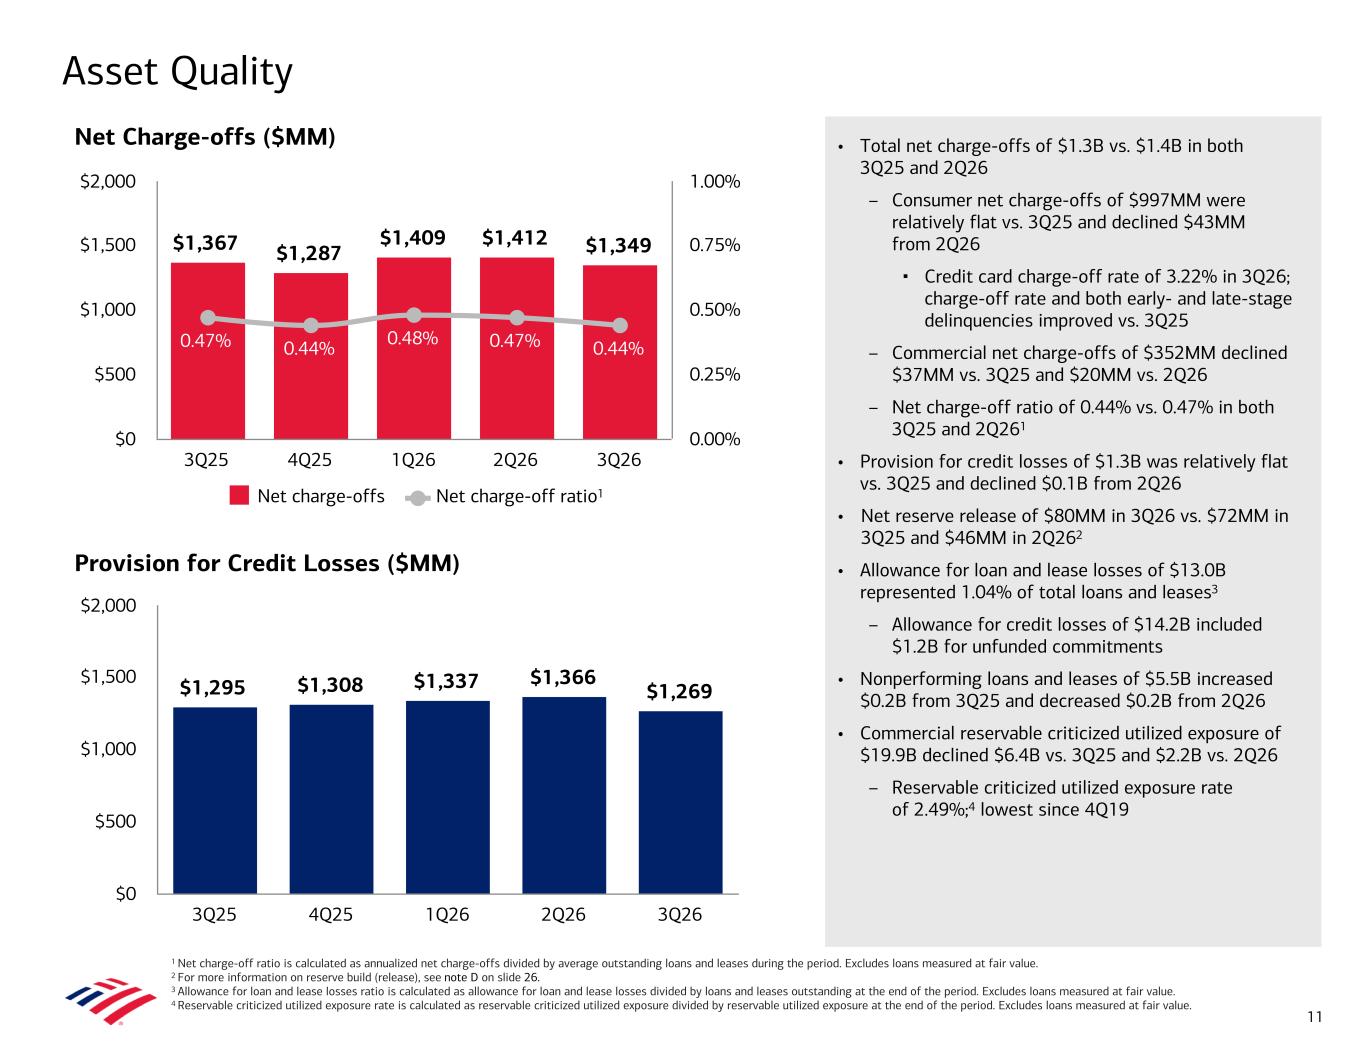
Asset Quality 1 Net charge-off ratio is calculated as annualized net charge-offs divided by average outstanding loans and leases during the period. Excludes loans measured at fair value. 2 For more information on reserve build (release), see note D on slide 26. 3 Allowance for loan and lease losses ratio is calculated as allowance for loan and lease losses divided by loans and leases outstanding at the end of the period. Excludes loans measured at fair value. 4 Reservable criticized utilized exposure rate is calculated as reservable criticized utilized exposure divided by reservable utilized exposure at the end of the period. Excludes loans measured at fair value. Provision for Credit Losses ($MM) Net Charge-offs ($MM) $1,295 $1,308 $1,337 $1,366 $1,269 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $500 $1,000 $1,500 $2,000 $1,367 $1,287 $1,409 $1,412 $1,349 0.47% 0.44% 0.48% 0.47% 0.44% Net charge-offs Net charge-off ratio 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $500 $1,000 $1,500 $2,000 0.00% 0.25% 0.50% 0.75% 1.00% 11 • Total net charge-offs of $1.3B vs. $1.4B in both 3Q25 and 2Q26 – Consumer net charge-offs of $997MM were relatively flat vs. 3Q25 and declined $43MM from 2Q26 ▪ Credit card charge-off rate of 3.22% in 3Q26; charge-off rate and both early- and late-stage delinquencies improved vs. 3Q25 – Commercial net charge-offs of $352MM declined $37MM vs. 3Q25 and $20MM vs. 2Q26 – Net charge-off ratio of 0.44% vs. 0.47% in both 3Q25 and 2Q261 • Provision for credit losses of $1.3B was relatively flat vs. 3Q25 and declined $0.1B from 2Q26 • Net reserve release of $80MM in 3Q26 vs. $72MM in 3Q25 and $46MM in 2Q262 • Allowance for loan and lease losses of $13.0B represented 1.04% of total loans and leases3 – Allowance for credit losses of $14.2B included $1.2B for unfunded commitments • Nonperforming loans and leases of $5.5B increased $0.2B from 3Q25 and decreased $0.2B from 2Q26 • Commercial reservable criticized utilized exposure of $19.9B declined $6.4B vs. 3Q25 and $2.2B vs. 2Q26 – Reservable criticized utilized exposure rate of 2.49%;4 lowest since 4Q19 1
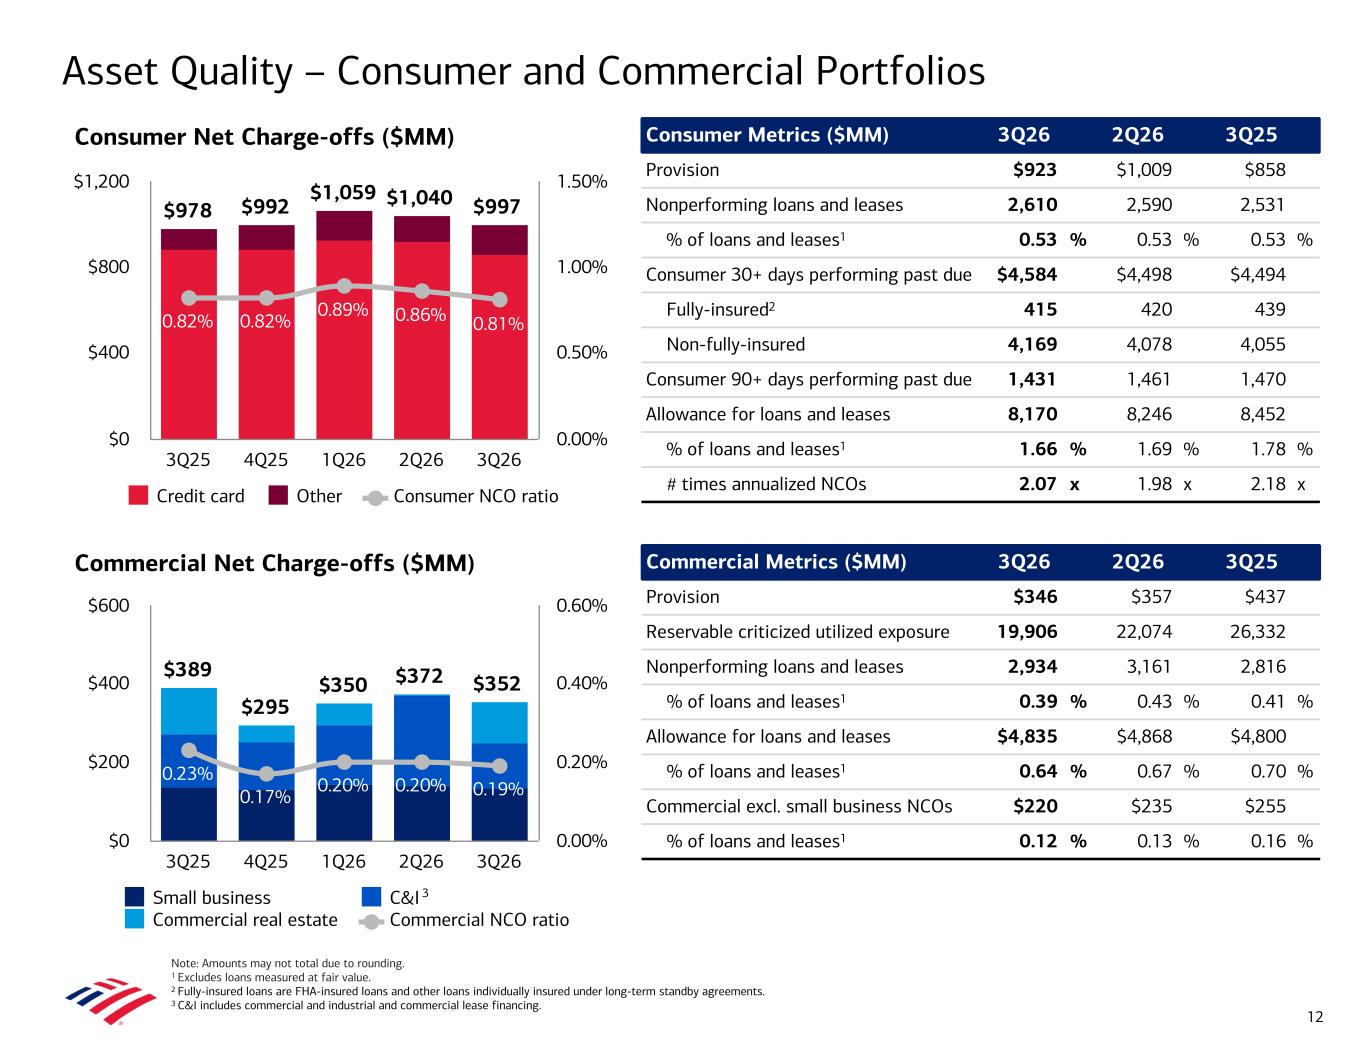
Commercial Net Charge-offs ($MM) Consumer Net Charge-offs ($MM) Asset Quality – Consumer and Commercial Portfolios $389 $295 $350 $372 $352 0.23% 0.17% 0.20% 0.20% 0.19% Small business C&I Commercial real estate Commercial NCO ratio 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $200 $400 $600 0.00% 0.20% 0.40% 0.60% $978 $992 $1,059 $1,040 $997 0.82% 0.82% 0.89% 0.86% 0.81% Credit card Other Consumer NCO ratio 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $400 $800 $1,200 0.00% 0.50% 1.00% 1.50% Commercial Metrics ($MM) 3Q26 2Q26 3Q25 Provision $346 $357 $437 Reservable criticized utilized exposure 19,906 22,074 26,332 Nonperforming loans and leases 2,934 3,161 2,816 % of loans and leases1 0.39 % 0.43 % 0.41 % Allowance for loans and leases $4,835 $4,868 $4,800 % of loans and leases1 0.64 % 0.67 % 0.70 % Commercial excl. small business NCOs $220 $235 $255 % of loans and leases1 0.12 % 0.13 % 0.16 % Consumer Metrics ($MM) 3Q26 2Q26 3Q25 Provision $923 $1,009 $858 Nonperforming loans and leases 2,610 2,590 2,531 % of loans and leases1 0.53 % 0.53 % 0.53 % Consumer 30+ days performing past due $4,584 $4,498 $4,494 Fully-insured2 415 420 439 Non-fully-insured 4,169 4,078 4,055 Consumer 90+ days performing past due 1,431 1,461 1,470 Allowance for loans and leases 8,170 8,246 8,452 % of loans and leases1 1.66 % 1.69 % 1.78 % # times annualized NCOs 2.07 x 1.98 x 2.18 x 12 3 Note: Amounts may not total due to rounding. 1 Excludes loans measured at fair value. 2 Fully-insured loans are FHA-insured loans and other loans individually insured under long-term standby agreements. 3 C&I includes commercial and industrial and commercial lease financing.
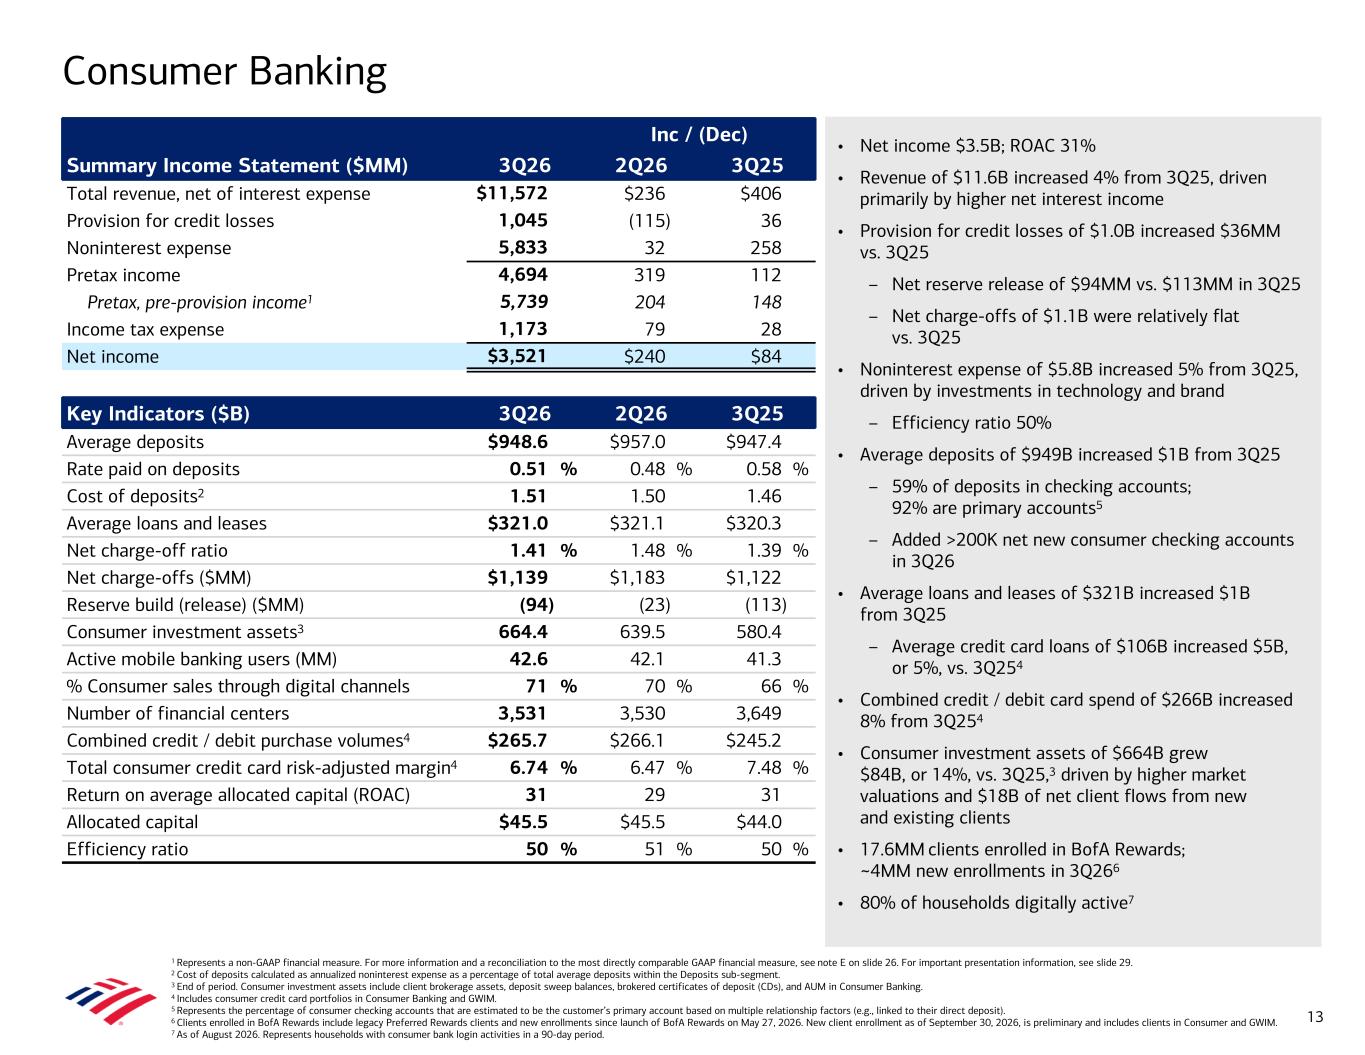
Consumer Banking 1 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note E on slide 26. For important presentation information, see slide 29. 2 Cost of deposits calculated as annualized noninterest expense as a percentage of total average deposits within the Deposits sub-segment. 3 End of period. Consumer investment assets include client brokerage assets, deposit sweep balances, brokered certificates of deposit (CDs), and AUM in Consumer Banking. 4 Includes consumer credit card portfolios in Consumer Banking and GWIM. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 Clients enrolled in BofA Rewards include legacy Preferred Rewards clients and new enrollments since launch of BofA Rewards on May 27, 2026. New client enrollment as of September 30, 2026, is preliminary and includes clients in Consumer and GWIM. 7 As of August 2026. Represents households with consumer bank login activities in a 90-day period. Inc / (Dec) Summary Income Statement ($MM) 3Q26 2Q26 3Q25 Total revenue, net of interest expense $11,572 $236 $406 Provision for credit losses 1,045 (115) 36 Noninterest expense 5,833 32 258 Pretax income 4,694 319 112 Pretax, pre-provision income1 5,739 204 148 Income tax expense 1,173 79 28 Net income $3,521 $240 $84 Key Indicators ($B) 3Q26 2Q26 3Q25 Average deposits $948.6 $957.0 $947.4 Rate paid on deposits 0.51 % 0.48 % 0.58 % Cost of deposits2 1.51 1.50 1.46 Average loans and leases $321.0 $321.1 $320.3 Net charge-off ratio 1.41 % 1.48 % 1.39 % Net charge-offs ($MM) $1,139 $1,183 $1,122 Reserve build (release) ($MM) (94) (23) (113) Consumer investment assets3 664.4 639.5 580.4 Active mobile banking users (MM) 42.6 42.1 41.3 % Consumer sales through digital channels 71 % 70 % 66 % Number of financial centers 3,531 3,530 3,649 Combined credit / debit purchase volumes4 $265.7 $266.1 $245.2 Total consumer credit card risk-adjusted margin4 6.74 % 6.47 % 7.48 % Return on average allocated capital (ROAC) 31 29 31 Allocated capital $45.5 $45.5 $44.0 Efficiency ratio 50 % 51 % 50 % 13 • Net income $3.5B; ROAC 31% • Revenue of $11.6B increased 4% from 3Q25, driven primarily by higher net interest income • Provision for credit losses of $1.0B increased $36MM vs. 3Q25 – Net reserve release of $94MM vs. $113MM in 3Q25 – Net charge-offs of $1.1B were relatively flat vs. 3Q25 • Noninterest expense of $5.8B increased 5% from 3Q25, driven by investments in technology and brand – Efficiency ratio 50% • Average deposits of $949B increased $1B from 3Q25 – 59% of deposits in checking accounts; 92% are primary accounts5 – Added >200K net new consumer checking accounts in 3Q26 • Average loans and leases of $321B increased $1B from 3Q25 – Average credit card loans of $106B increased $5B, or 5%, vs. 3Q254 • Combined credit / debit card spend of $266B increased 8% from 3Q254 • Consumer investment assets of $664B grew $84B, or 14%, vs. 3Q25,3 driven by higher market valuations and $18B of net client flows from new and existing clients • 17.6MM clients enrolled in BofA Rewards; ~4MM new enrollments in 3Q266 • 80% of households digitally active7
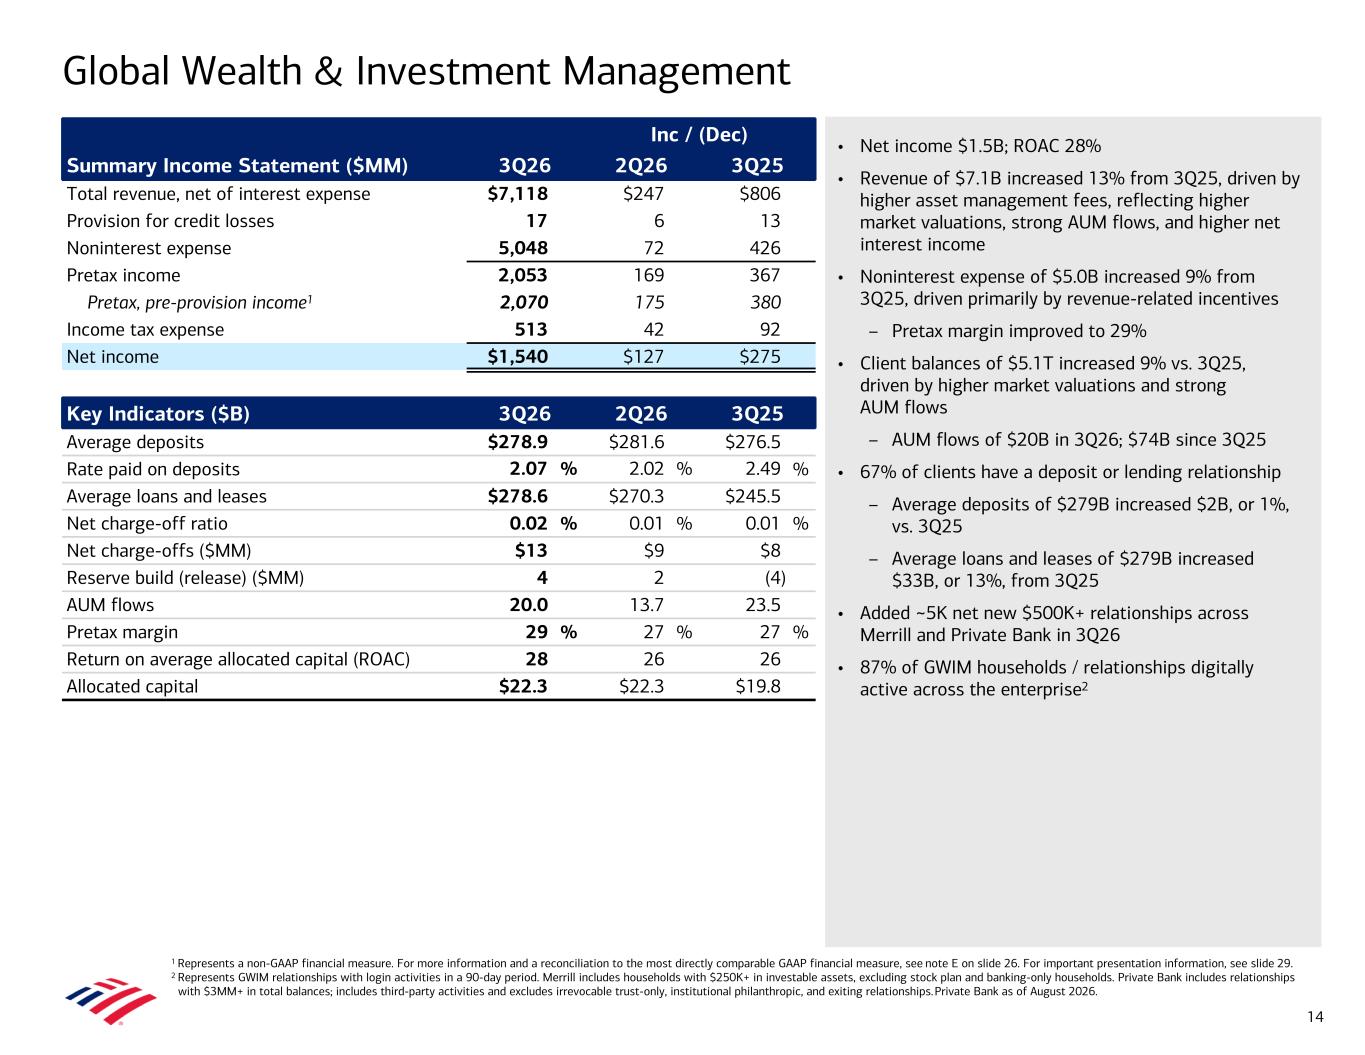
• Net income $1.5B; ROAC 28% • Revenue of $7.1B increased 13% from 3Q25, driven by higher asset management fees, reflecting higher market valuations, strong AUM flows, and higher net interest income • Noninterest expense of $5.0B increased 9% from 3Q25, driven primarily by revenue-related incentives – Pretax margin improved to 29% • Client balances of $5.1T increased 9% vs. 3Q25, driven by higher market valuations and strong AUM flows – AUM flows of $20B in 3Q26; $74B since 3Q25 • 67% of clients have a deposit or lending relationship – Average deposits of $279B increased $2B, or 1%, vs. 3Q25 – Average loans and leases of $279B increased $33B, or 13%, from 3Q25 • Added ~5K net new $500K+ relationships across Merrill and Private Bank in 3Q26 • 87% of GWIM households / relationships digitally active across the enterprise2 Global Wealth & Investment Management 1 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note E on slide 26. For important presentation information, see slide 29. 2 Represents GWIM relationships with login activities in a 90-day period. Merrill includes households with $250K+ in investable assets, excluding stock plan and banking-only households. Private Bank includes relationships with $3MM+ in total balances; includes third-party activities and excludes irrevocable trust-only, institutional philanthropic, and exiting relationships. Private Bank as of August 2026. Inc / (Dec) Summary Income Statement ($MM) 3Q26 2Q26 3Q25 Total revenue, net of interest expense $7,118 $247 $806 Provision for credit losses 17 6 13 Noninterest expense 5,048 72 426 Pretax income 2,053 169 367 Pretax, pre-provision income1 2,070 175 380 Income tax expense 513 42 92 Net income $1,540 $127 $275 Key Indicators ($B) 3Q26 2Q26 3Q25 Average deposits $278.9 $281.6 $276.5 Rate paid on deposits 2.07 % 2.02 % 2.49 % Average loans and leases $278.6 $270.3 $245.5 Net charge-off ratio 0.02 % 0.01 % 0.01 % Net charge-offs ($MM) $13 $9 $8 Reserve build (release) ($MM) 4 2 (4) AUM flows 20.0 13.7 23.5 Pretax margin 29 % 27 % 27 % Return on average allocated capital (ROAC) 28 26 26 Allocated capital $22.3 $22.3 $19.8 14
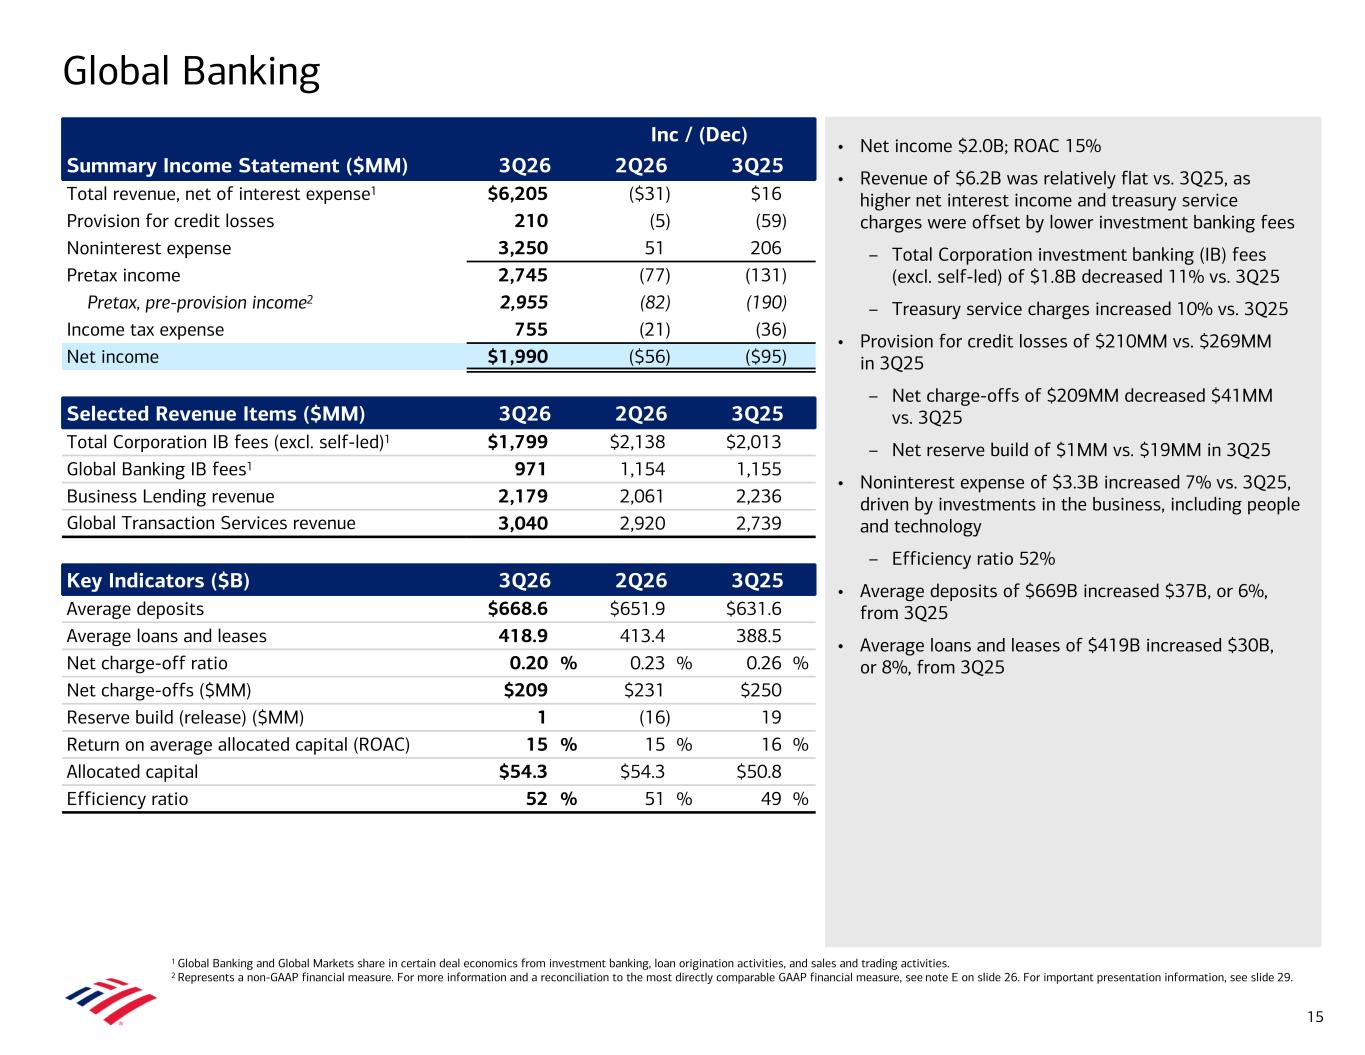
Global Banking 1 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note E on slide 26. For important presentation information, see slide 29. Inc / (Dec) Summary Income Statement ($MM) 3Q26 2Q26 3Q25 Total revenue, net of interest expense1 $6,205 ($31) $16 Provision for credit losses 210 (5) (59) Noninterest expense 3,250 51 206 Pretax income 2,745 (77) (131) Pretax, pre-provision income2 2,955 (82) (190) Income tax expense 755 (21) (36) Net income $1,990 ($56) ($95) Selected Revenue Items ($MM) 3Q26 2Q26 3Q25 Total Corporation IB fees (excl. self-led)1 $1,799 $2,138 $2,013 Global Banking IB fees1 971 1,154 1,155 Business Lending revenue 2,179 2,061 2,236 Global Transaction Services revenue 3,040 2,920 2,739 Key Indicators ($B) 3Q26 2Q26 3Q25 Average deposits $668.6 $651.9 $631.6 Average loans and leases 418.9 413.4 388.5 Net charge-off ratio 0.20 % 0.23 % 0.26 % Net charge-offs ($MM) $209 $231 $250 Reserve build (release) ($MM) 1 (16) 19 Return on average allocated capital (ROAC) 15 % 15 % 16 % Allocated capital $54.3 $54.3 $50.8 Efficiency ratio 52 % 51 % 49 % 15 • Net income $2.0B; ROAC 15% • Revenue of $6.2B was relatively flat vs. 3Q25, as higher net interest income and treasury service charges were offset by lower investment banking fees – Total Corporation investment banking (IB) fees (excl. self-led) of $1.8B decreased 11% vs. 3Q25 – Treasury service charges increased 10% vs. 3Q25 • Provision for credit losses of $210MM vs. $269MM in 3Q25 – Net charge-offs of $209MM decreased $41MM vs. 3Q25 – Net reserve build of $1MM vs. $19MM in 3Q25 • Noninterest expense of $3.3B increased 7% vs. 3Q25, driven by investments in the business, including people and technology – Efficiency ratio 52% • Average deposits of $669B increased $37B, or 6%, from 3Q25 • Average loans and leases of $419B increased $30B, or 8%, from 3Q25
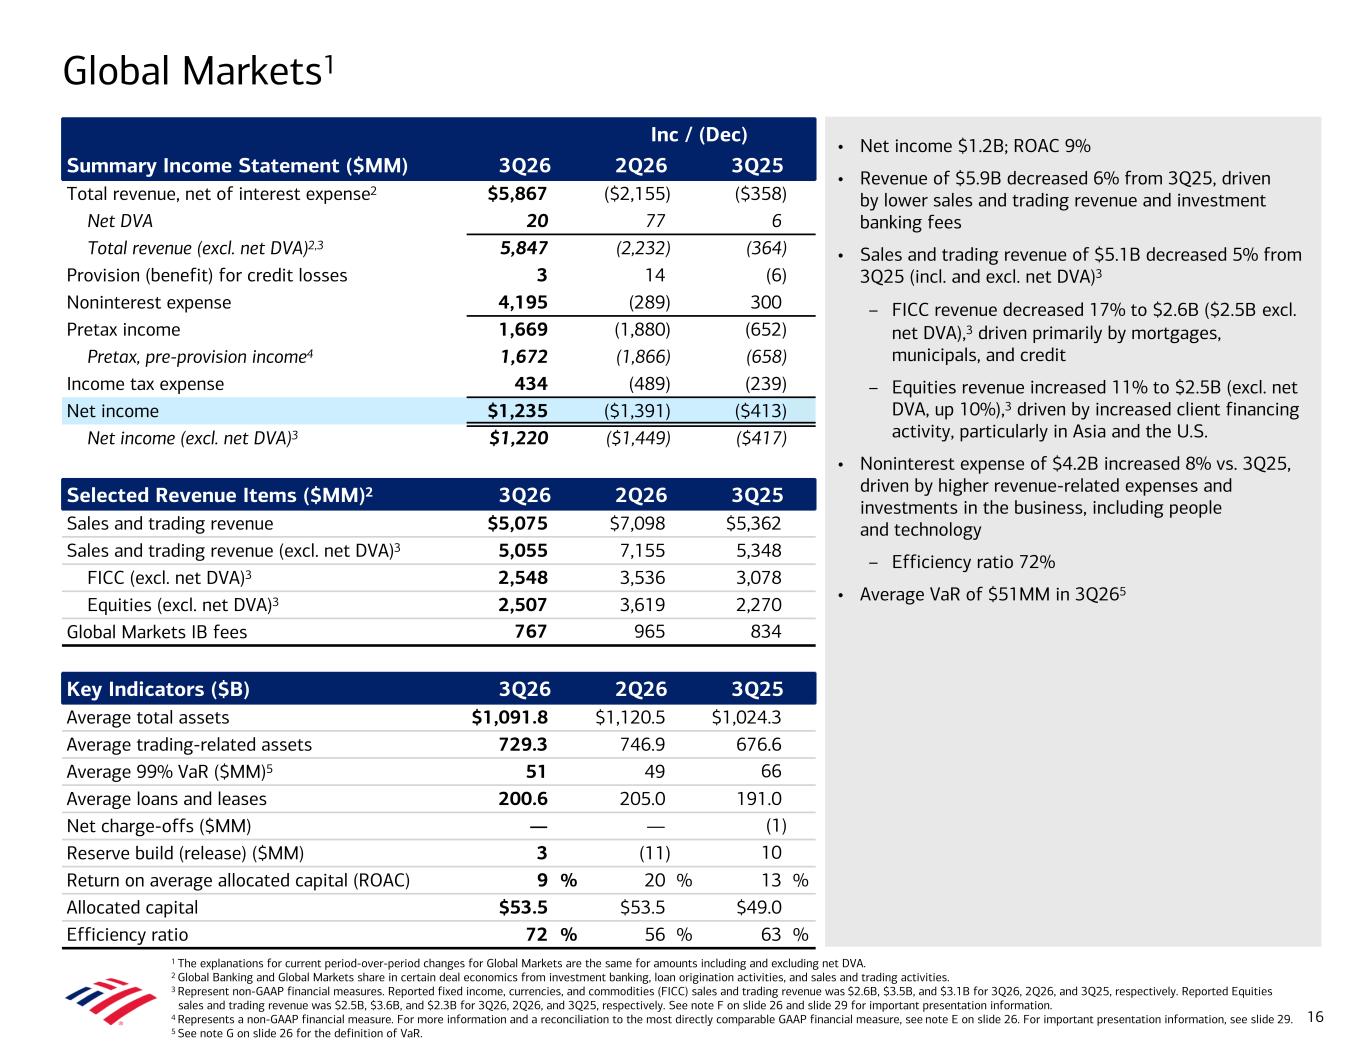
Global Markets1 1 The explanations for current period-over-period changes for Global Markets are the same for amounts including and excluding net DVA. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Represent non-GAAP financial measures. Reported fixed income, currencies, and commodities (FICC) sales and trading revenue was $2.6B, $3.5B, and $3.1B for 3Q26, 2Q26, and 3Q25, respectively. Reported Equities sales and trading revenue was $2.5B, $3.6B, and $2.3B for 3Q26, 2Q26, and 3Q25, respectively. See note F on slide 26 and slide 29 for important presentation information. 4 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note E on slide 26. For important presentation information, see slide 29. 5 See note G on slide 26 for the definition of VaR. Inc / (Dec) Summary Income Statement ($MM) 3Q26 2Q26 3Q25 Total revenue, net of interest expense2 $5,867 ($2,155) ($358) Net DVA 20 77 6 Total revenue (excl. net DVA)2,3 5,847 (2,232) (364) Provision (benefit) for credit losses 3 14 (6) Noninterest expense 4,195 (289) 300 Pretax income 1,669 (1,880) (652) Pretax, pre-provision income4 1,672 (1,866) (658) Income tax expense 434 (489) (239) Net income $1,235 ($1,391) ($413) Net income (excl. net DVA)3 $1,220 ($1,449) ($417) Selected Revenue Items ($MM)2 3Q26 2Q26 3Q25 Sales and trading revenue $5,075 $7,098 $5,362 Sales and trading revenue (excl. net DVA)3 5,055 7,155 5,348 FICC (excl. net DVA)3 2,548 3,536 3,078 Equities (excl. net DVA)3 2,507 3,619 2,270 Global Markets IB fees 767 965 834 Key Indicators ($B) 3Q26 2Q26 3Q25 Average total assets $1,091.8 $1,120.5 $1,024.3 Average trading-related assets 729.3 746.9 676.6 Average 99% VaR ($MM)5 51 49 66 Average loans and leases 200.6 205.0 191.0 Net charge-offs ($MM) — — (1) Reserve build (release) ($MM) 3 (11) 10 Return on average allocated capital (ROAC) 9 % 20 % 13 % Allocated capital $53.5 $53.5 $49.0 Efficiency ratio 72 % 56 % 63 % 16 • Net income $1.2B; ROAC 9% • Revenue of $5.9B decreased 6% from 3Q25, driven by lower sales and trading revenue and investment banking fees • Sales and trading revenue of $5.1B decreased 5% from 3Q25 (incl. and excl. net DVA)3 – FICC revenue decreased 17% to $2.6B ($2.5B excl. net DVA),3 driven primarily by mortgages, municipals, and credit – Equities revenue increased 11% to $2.5B (excl. net DVA, up 10%),3 driven by increased client financing activity, particularly in Asia and the U.S. • Noninterest expense of $4.2B increased 8% vs. 3Q25, driven by higher revenue-related expenses and investments in the business, including people and technology – Efficiency ratio 72% • Average VaR of $51MM in 3Q265
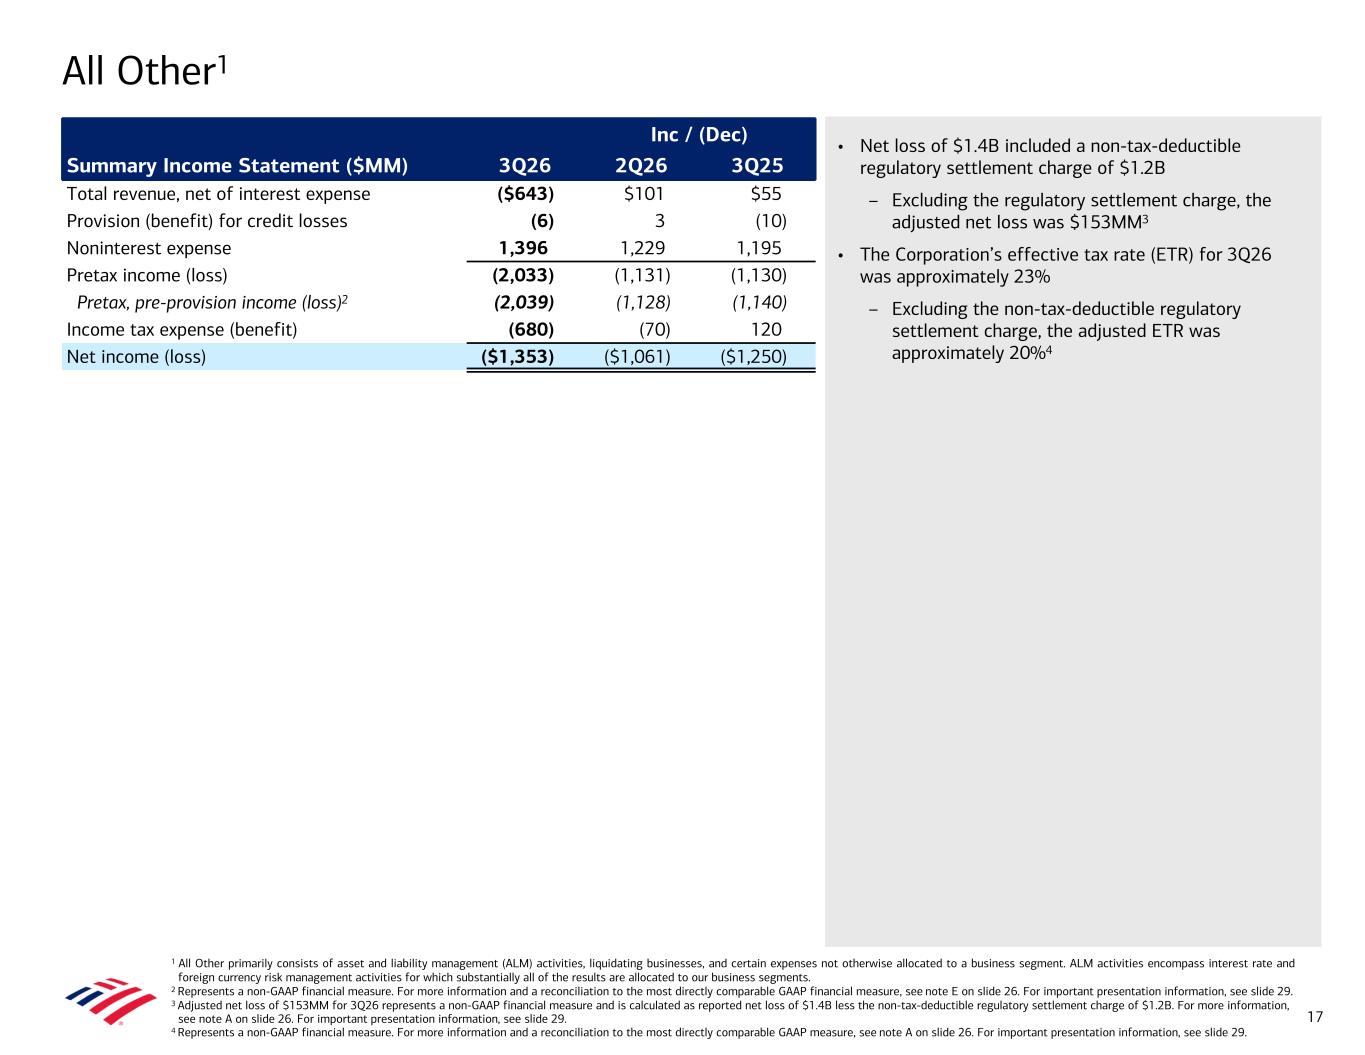
• Net loss of $1.4B included a non-tax-deductible regulatory settlement charge of $1.2B – Excluding the regulatory settlement charge, the adjusted net loss was $153MM3 • The Corporation’s effective tax rate (ETR) for 3Q26 was approximately 23% – Excluding the non-tax-deductible regulatory settlement charge, the adjusted ETR was approximately 20%4 All Other1 1 All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses, and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note E on slide 26. For important presentation information, see slide 29. 3 Adjusted net loss of $153MM for 3Q26 represents a non-GAAP financial measure and is calculated as reported net loss of $1.4B less the non-tax-deductible regulatory settlement charge of $1.2B. For more information, see note A on slide 26. For important presentation information, see slide 29. 4 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP measure, see note A on slide 26. For important presentation information, see slide 29. Inc / (Dec) Summary Income Statement ($MM) 3Q26 2Q26 3Q25 Total revenue, net of interest expense ($643) $101 $55 Provision (benefit) for credit losses (6) 3 (10) Noninterest expense 1,396 1,229 1,195 Pretax income (loss) (2,033) (1,131) (1,130) Pretax, pre-provision income (loss)2 (2,039) (1,128) (1,140) Income tax expense (benefit) (680) (70) 120 Net income (loss) ($1,353) ($1,061) ($1,250) 17
Supplemental Business Segment Trends
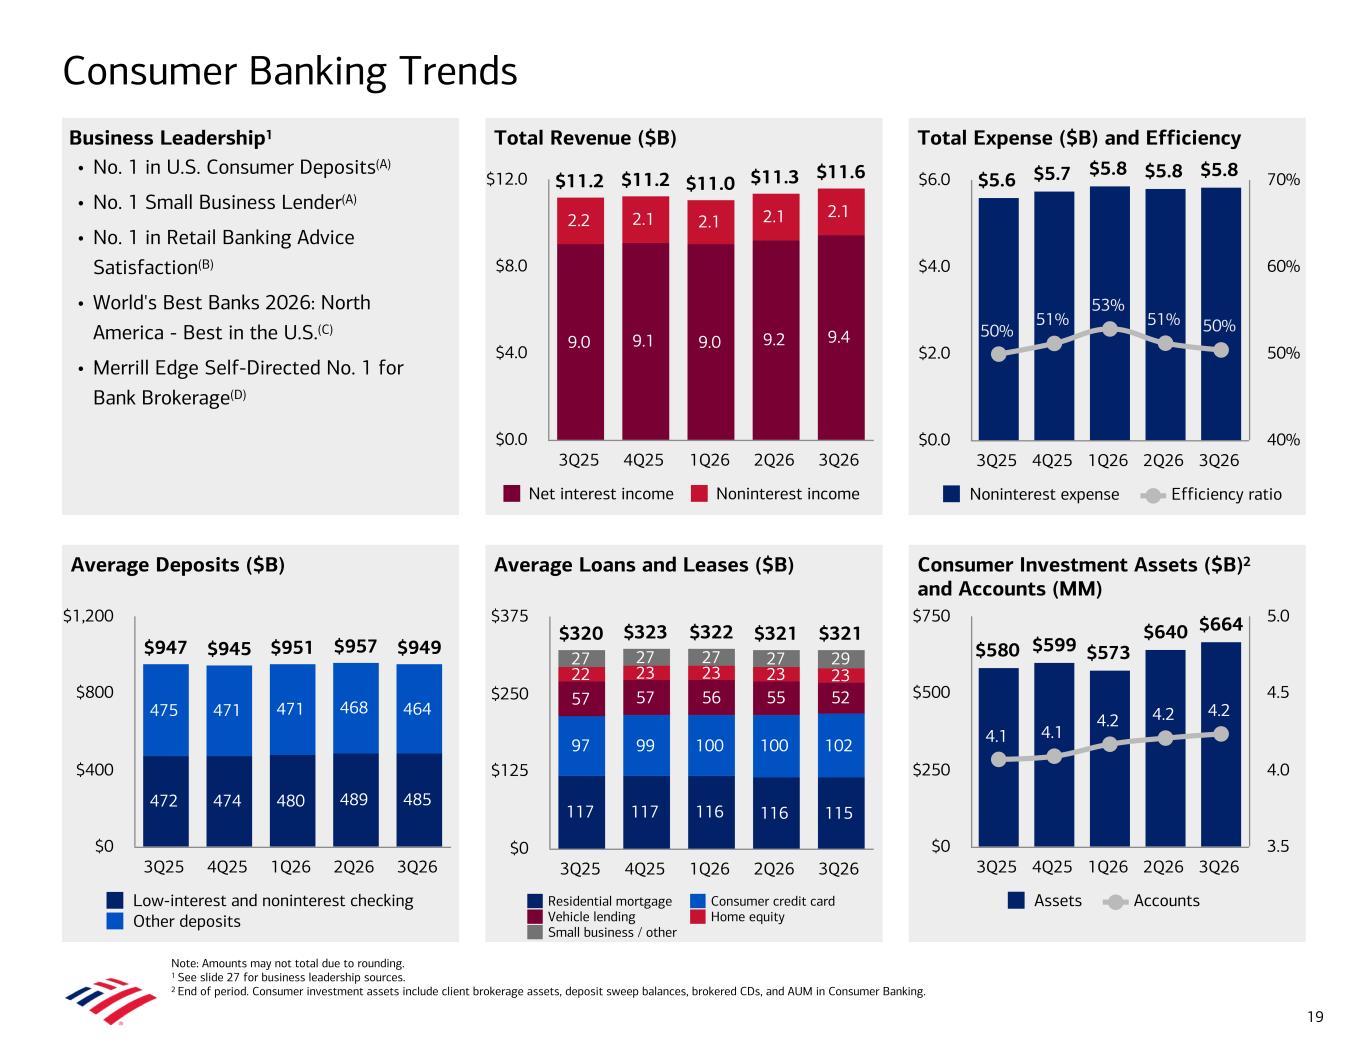
Total Expense ($B) and Efficiency Total Revenue ($B) Average Deposits ($B) Consumer Investment Assets ($B)2 and Accounts (MM) Average Loans and Leases ($B) Consumer Banking Trends Note: Amounts may not total due to rounding. 1 See slide 27 for business leadership sources. 2 End of period. Consumer investment assets include client brokerage assets, deposit sweep balances, brokered CDs, and AUM in Consumer Banking. $11.2 $11.2 $11.0 $11.3 $11.6 9.0 9.1 9.0 9.2 9.4 2.2 2.1 2.1 2.1 2.1 Net interest income Noninterest income 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $4.0 $8.0 $12.0 $5.6 $5.7 $5.8 $5.8 $5.8 50% 51% 53% 51% 50% Noninterest expense Efficiency ratio 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $2.0 $4.0 $6.0 40% 50% 60% 70% $947 $945 $951 $957 $949 472 474 480 489 485 475 471 471 468 464 Low-interest and noninterest checking Other deposits 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $400 $800 $1,200 $320 $323 $322 $321 $321 117 117 116 116 115 97 99 100 100 102 57 57 56 55 52 22 23 23 23 23 27 27 27 27 29 Residential mortgage Consumer credit card Vehicle lending Home equity Small business / other 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $125 $250 $375 19 $580 $599 $573 $640 $664 4.1 4.1 4.2 4.2 4.2 Assets Accounts 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $250 $500 $750 3.5 4.0 4.5 5.0 Business Leadership1 • No. 1 in U.S. Consumer Deposits(A) • No. 1 Small Business Lender(A) • No. 1 in Retail Banking Advice Satisfaction(B) • World's Best Banks 2026: North America - Best in the U.S.(C) • Merrill Edge Self-Directed No. 1 for Bank Brokerage(D)
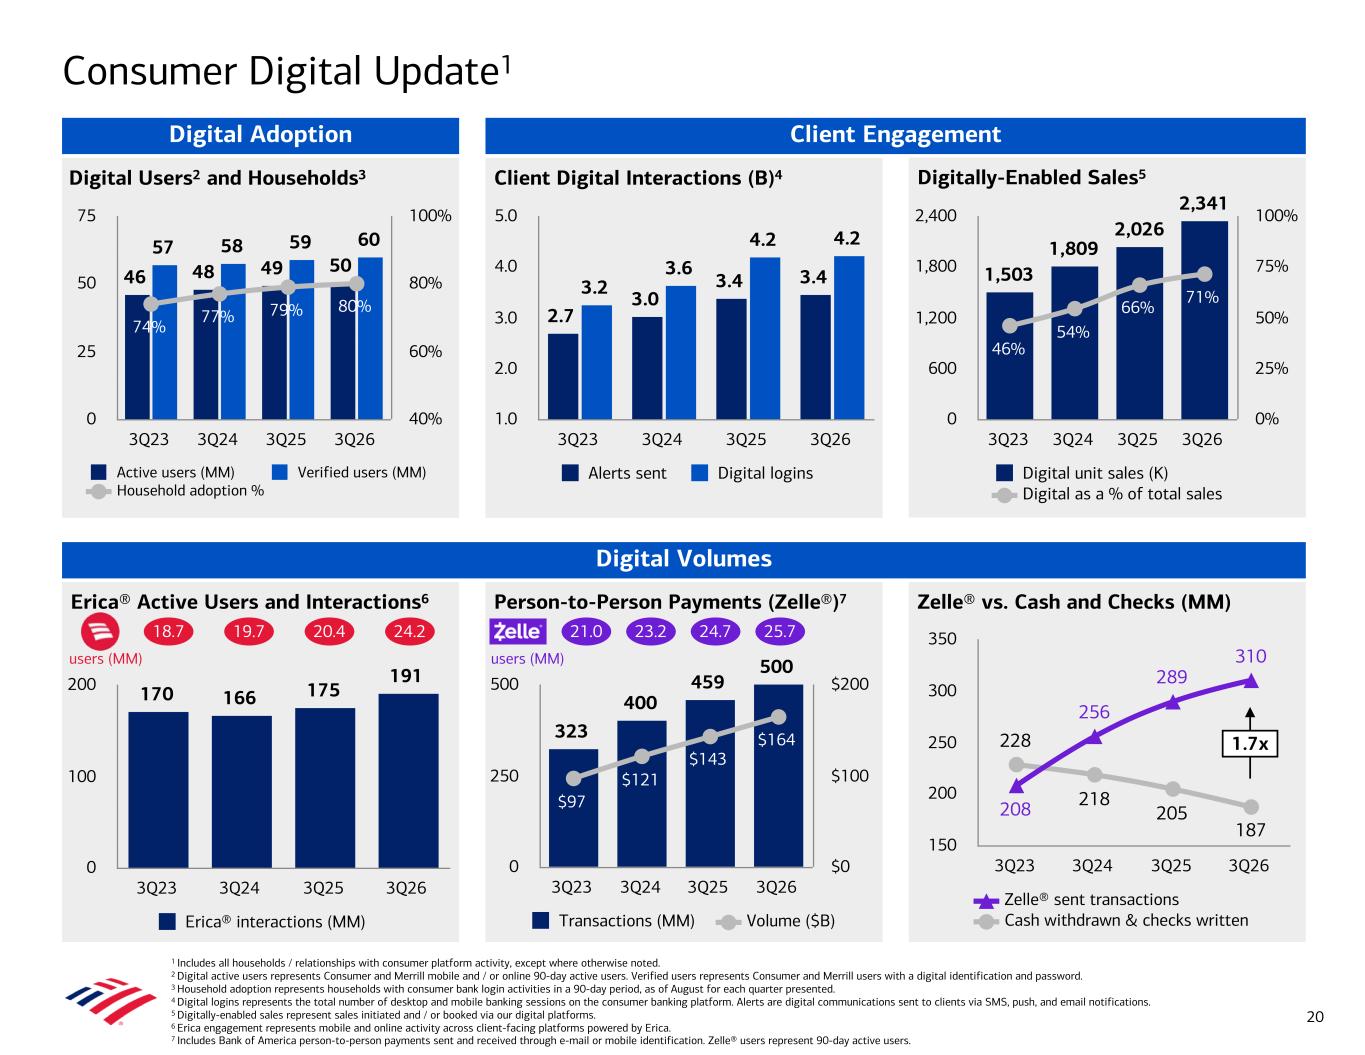
Erica® Active Users and Interactions6 Zelle® vs. Cash and Checks (MM) Digitally-Enabled Sales5Digital Users2 and Households3 Client Digital Interactions (B)4 1,503 1,809 2,026 2,341 46% 54% 66% 71% Digital unit sales (K) Digital as a % of total sales 3Q23 3Q24 3Q25 3Q26 0 600 1,200 1,800 2,400 0% 25% 50% 75% 100% 2.7 3.0 3.4 3.43.2 3.6 4.2 4.2 Alerts sent Digital logins 3Q23 3Q24 3Q25 3Q26 1.0 2.0 3.0 4.0 5.0 46 48 49 50 57 58 59 60 74% 77% 79% 80% Active users (MM) Verified users (MM) Household adoption % 3Q23 3Q24 3Q25 3Q26 0 25 50 75 40% 60% 80% 100% Client Engagement Person-to-Person Payments (Zelle®)7 Digital Volumes 323 400 459 500 $97 $121 $143 $164 Transactions (MM) Volume ($B) 3Q23 3Q24 3Q25 3Q26 0 250 500 $0 $100 $200 Consumer Digital Update1 1 Includes all households / relationships with consumer platform activity, except where otherwise noted. 2 Digital active users represents Consumer and Merrill mobile and / or online 90-day active users. Verified users represents Consumer and Merrill users with a digital identification and password. 3 Household adoption represents households with consumer bank login activities in a 90-day period, as of August for each quarter presented. 4 Digital logins represents the total number of desktop and mobile banking sessions on the consumer banking platform. Alerts are digital communications sent to clients via SMS, push, and email notifications. 5 Digitally-enabled sales represent sales initiated and / or booked via our digital platforms. 6 Erica engagement represents mobile and online activity across client-facing platforms powered by Erica. 7 Includes Bank of America person-to-person payments sent and received through e-mail or mobile identification. Zelle® users represent 90-day active users. 21.0 23.2 24.7 25.7 users (MM) 20 Digital Adoption 170 166 175 191 Erica® interactions (MM) 3Q23 3Q24 3Q25 3Q26 0 100 200 228 218 205 187 208 256 289 310 Zelle® sent transactions Cash withdrawn & checks written 3Q23 3Q24 3Q25 3Q26 150 200 250 300 350 1.7x 18.7 19.7 20.4 24.2 users (MM)
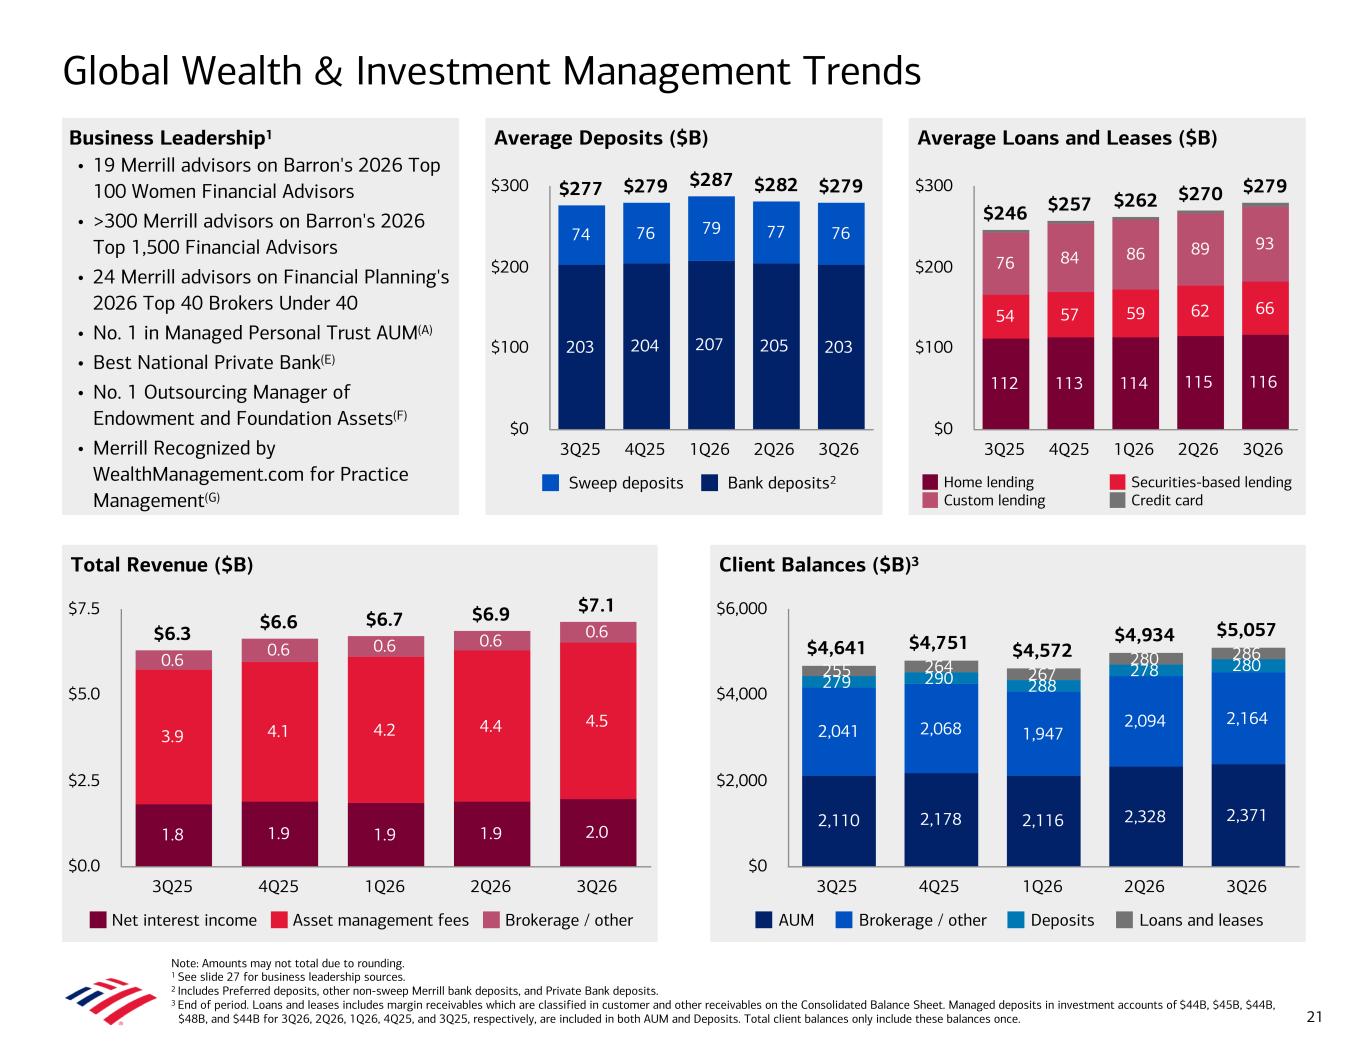
Note: Amounts may not total due to rounding. 1 See slide 27 for business leadership sources. 2 Includes Preferred deposits, other non-sweep Merrill bank deposits, and Private Bank deposits. 3 End of period. Loans and leases includes margin receivables which are classified in customer and other receivables on the Consolidated Balance Sheet. Managed deposits in investment accounts of $44B, $45B, $44B, $48B, and $44B for 3Q26, 2Q26, 1Q26, 4Q25, and 3Q25, respectively, are included in both AUM and Deposits. Total client balances only include these balances once. Average Deposits ($B) Global Wealth & Investment Management Trends Business Leadership1 • 19 Merrill advisors on Barron's 2026 Top 100 Women Financial Advisors • >300 Merrill advisors on Barron's 2026 Top 1,500 Financial Advisors • 24 Merrill advisors on Financial Planning's 2026 Top 40 Brokers Under 40 • No. 1 in Managed Personal Trust AUM(A) • Best National Private Bank(E) • No. 1 Outsourcing Manager of Endowment and Foundation Assets(F) • Merrill Recognized by WealthManagement.com for Practice Management(G) Average Loans and Leases ($B) Total Revenue ($B) Client Balances ($B)3 $6.3 $6.6 $6.7 $6.9 $7.1 1.8 1.9 1.9 1.9 2.0 3.9 4.1 4.2 4.4 4.5 0.6 0.6 0.6 0.6 0.6 Net interest income Asset management fees Brokerage / other 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $2.5 $5.0 $7.5 2,110 2,178 2,116 2,328 2,371 2,041 2,068 1,947 2,094 2,164 279 290 288 278 280255 264 267 280 286$4,641 $4,751 $4,572 $4,934 $5,057 AUM Brokerage / other Deposits Loans and leases 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $2,000 $4,000 $6,000 $246 $257 $262 $270 $279 112 113 114 115 116 54 57 59 62 66 76 84 86 89 93 Home lending Securities-based lending Custom lending Credit card 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $100 $200 $300$277 $279 $287 $282 $279 203 204 207 205 203 74 76 79 77 76 Sweep deposits Bank deposits 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $100 $200 $300 21 2
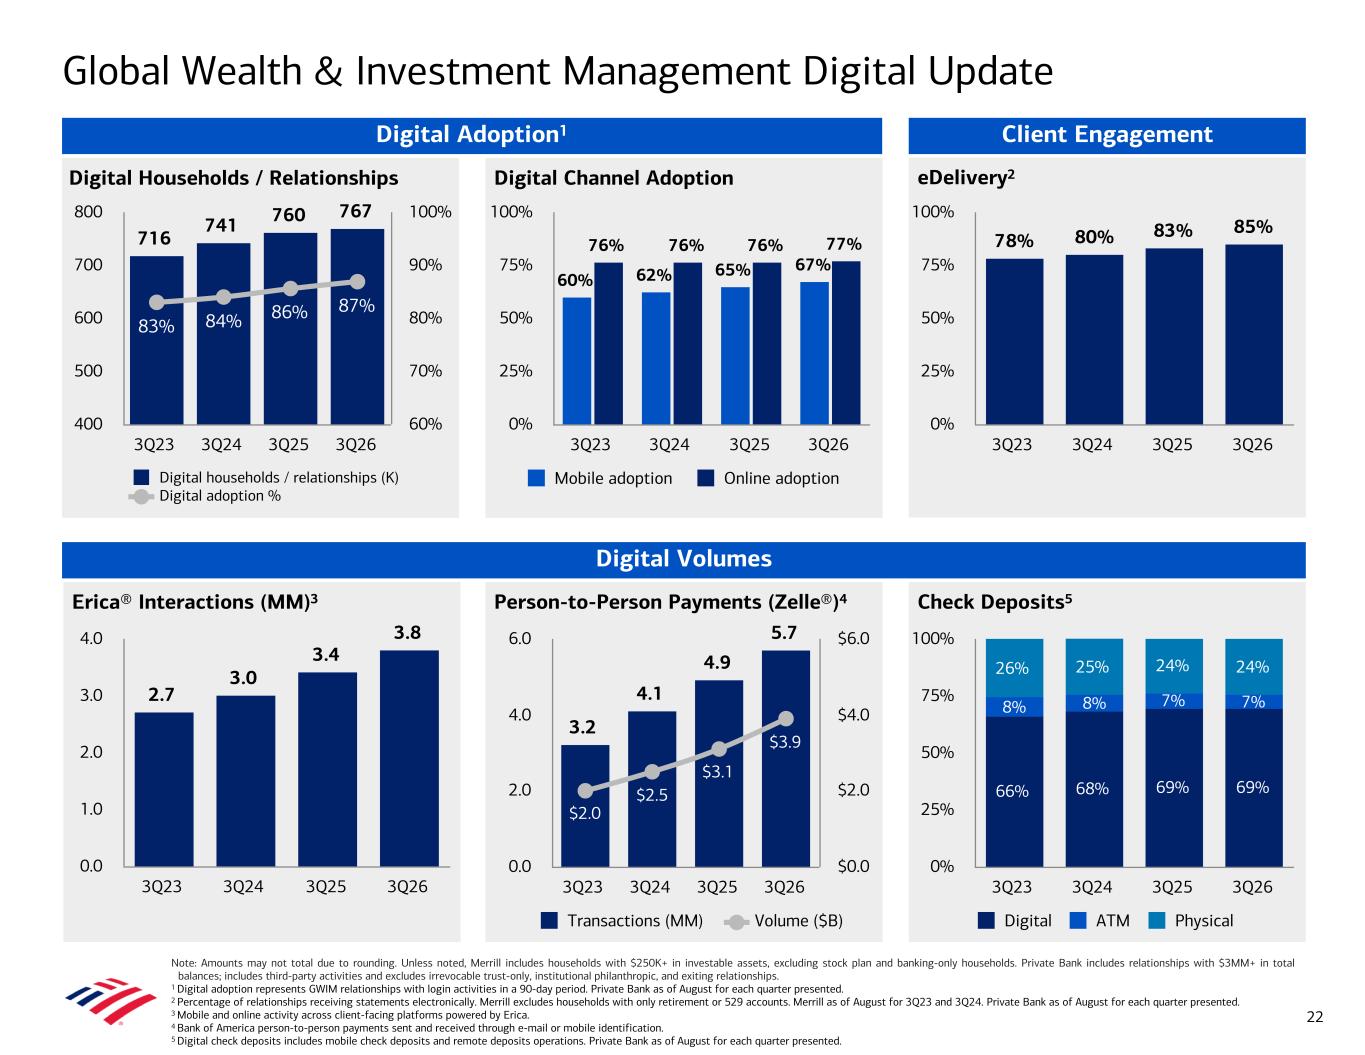
Erica® Interactions (MM)3 Person-to-Person Payments (Zelle®)4 Check Deposits5 eDelivery2Digital Households / Relationships Digital Channel Adoption 78% 80% 83% 85% 3Q23 3Q24 3Q25 3Q26 0% 25% 50% 75% 100% 60% 62% 65% 67% 76% 76% 76% 77% Mobile adoption Online adoption 3Q23 3Q24 3Q25 3Q26 0% 25% 50% 75% 100% 716 741 760 767 83% 84% 86% 87% Digital households / relationships (K) Digital adoption % 3Q23 3Q24 3Q25 3Q26 400 500 600 700 800 60% 70% 80% 90% 100% Client Engagement Digital Volumes Global Wealth & Investment Management Digital Update 22 Digital Adoption1 Note: Amounts may not total due to rounding. Unless noted, Merrill includes households with $250K+ in investable assets, excluding stock plan and banking-only households. Private Bank includes relationships with $3MM+ in total balances; includes third-party activities and excludes irrevocable trust-only, institutional philanthropic, and exiting relationships. 1 Digital adoption represents GWIM relationships with login activities in a 90-day period. Private Bank as of August for each quarter presented. 2 Percentage of relationships receiving statements electronically. Merrill excludes households with only retirement or 529 accounts. Merrill as of August for 3Q23 and 3Q24. Private Bank as of August for each quarter presented. 3 Mobile and online activity across client-facing platforms powered by Erica. 4 Bank of America person-to-person payments sent and received through e-mail or mobile identification. 5 Digital check deposits includes mobile check deposits and remote deposits operations. Private Bank as of August for each quarter presented. 2.7 3.0 3.4 3.8 3Q23 3Q24 3Q25 3Q26 0.0 1.0 2.0 3.0 4.0 3.2 4.1 4.9 5.7 $2.0 $2.5 $3.1 $3.9 Transactions (MM) Volume ($B) 3Q23 3Q24 3Q25 3Q26 0.0 2.0 4.0 6.0 $0.0 $2.0 $4.0 $6.0 66% 68% 69% 69% 8% 8% 7% 7% 26% 25% 24% 24% Digital ATM Physical 3Q23 3Q24 3Q25 3Q26 0% 25% 50% 75% 100%
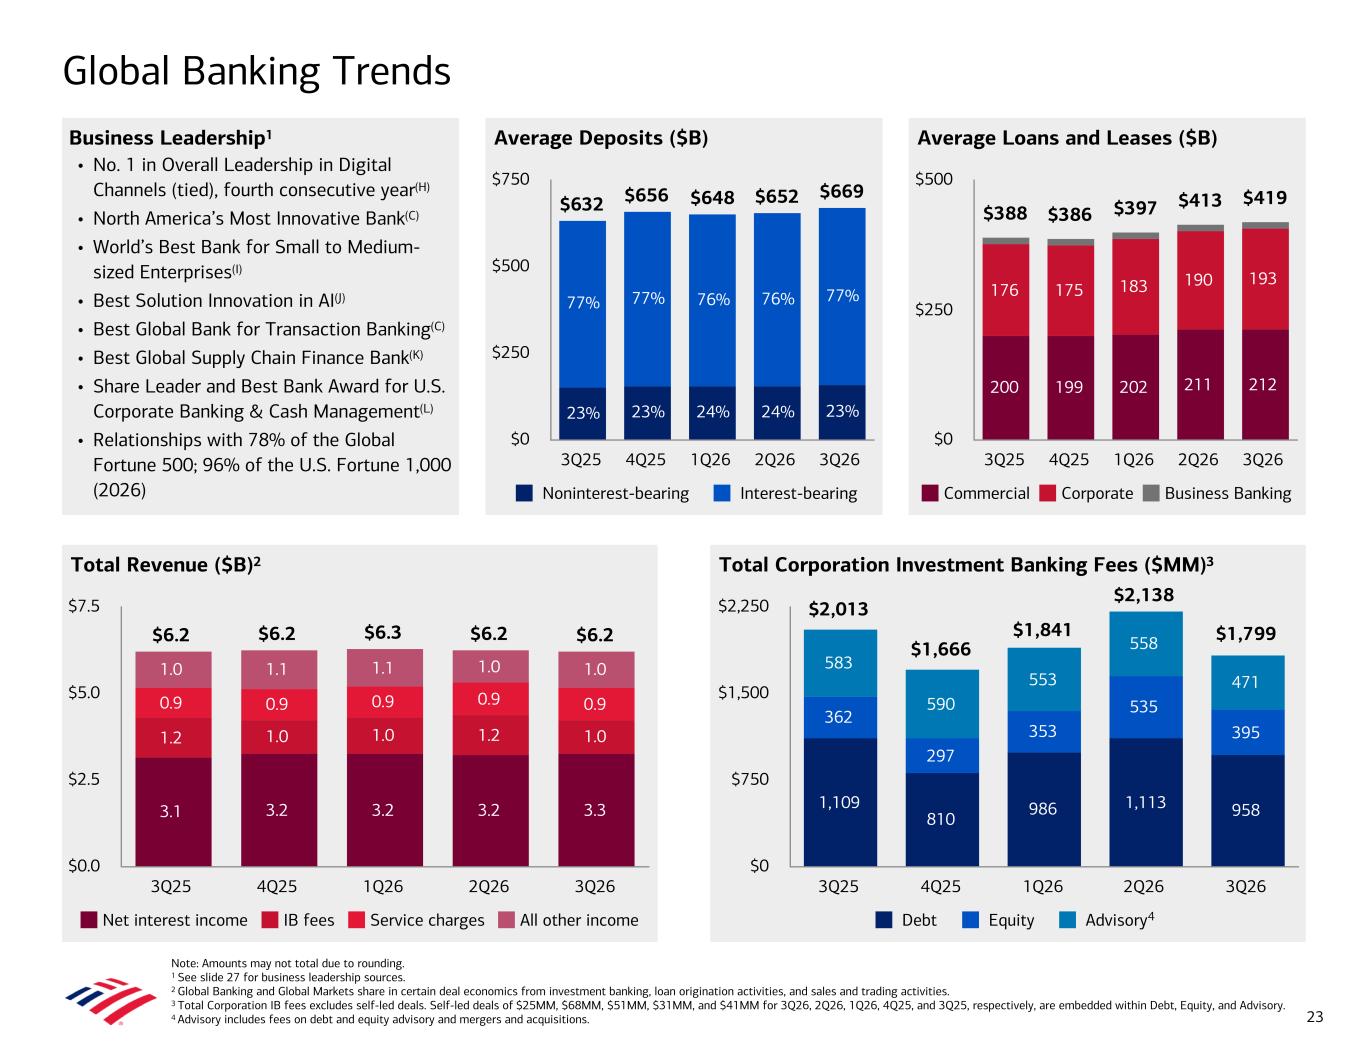
Global Banking Trends Note: Amounts may not total due to rounding. 1 See slide 27 for business leadership sources. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Total Corporation IB fees excludes self-led deals. Self-led deals of $25MM, $68MM, $51MM, $31MM, and $41MM for 3Q26, 2Q26, 1Q26, 4Q25, and 3Q25, respectively, are embedded within Debt, Equity, and Advisory. 4 Advisory includes fees on debt and equity advisory and mergers and acquisitions. Average Deposits ($B)Business Leadership1 • No. 1 in Overall Leadership in Digital Channels (tied), fourth consecutive year(H) • North America’s Most Innovative Bank(C) • World’s Best Bank for Small to Medium- sized Enterprises(I) • Best Solution Innovation in AI(J) • Best Global Bank for Transaction Banking(C) • Best Global Supply Chain Finance Bank(K) • Share Leader and Best Bank Award for U.S. Corporate Banking & Cash Management(L) • Relationships with 78% of the Global Fortune 500; 96% of the U.S. Fortune 1,000 (2026) Average Loans and Leases ($B) Total Revenue ($B)2 Total Corporation Investment Banking Fees ($MM)3 $6.2 $6.2 $6.3 $6.2 $6.2 3.1 3.2 3.2 3.2 3.3 1.2 1.0 1.0 1.2 1.0 0.9 0.9 0.9 0.9 0.9 1.0 1.1 1.1 1.0 1.0 Net interest income IB fees Service charges All other income 3Q25 4Q25 1Q26 2Q26 3Q26 $0.0 $2.5 $5.0 $7.5 1,109 810 986 1,113 958 362 297 353 535 395 583 590 553 558 471 $2,013 $1,666 $1,841 $2,138 $1,799 Debt Equity Advisory 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $750 $1,500 $2,250 200 199 202 211 212 176 175 183 190 193 $388 $386 $397 $413 $419 Commercial Corporate Business Banking 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $250 $500 4 $632 $656 $648 $652 $669 Noninterest-bearing Interest-bearing 3Q25 4Q25 1Q26 2Q26 3Q26 $0 $250 $500 $750 23 23% 23% 24% 24% 23% 77% 77% 76% 76% 77%
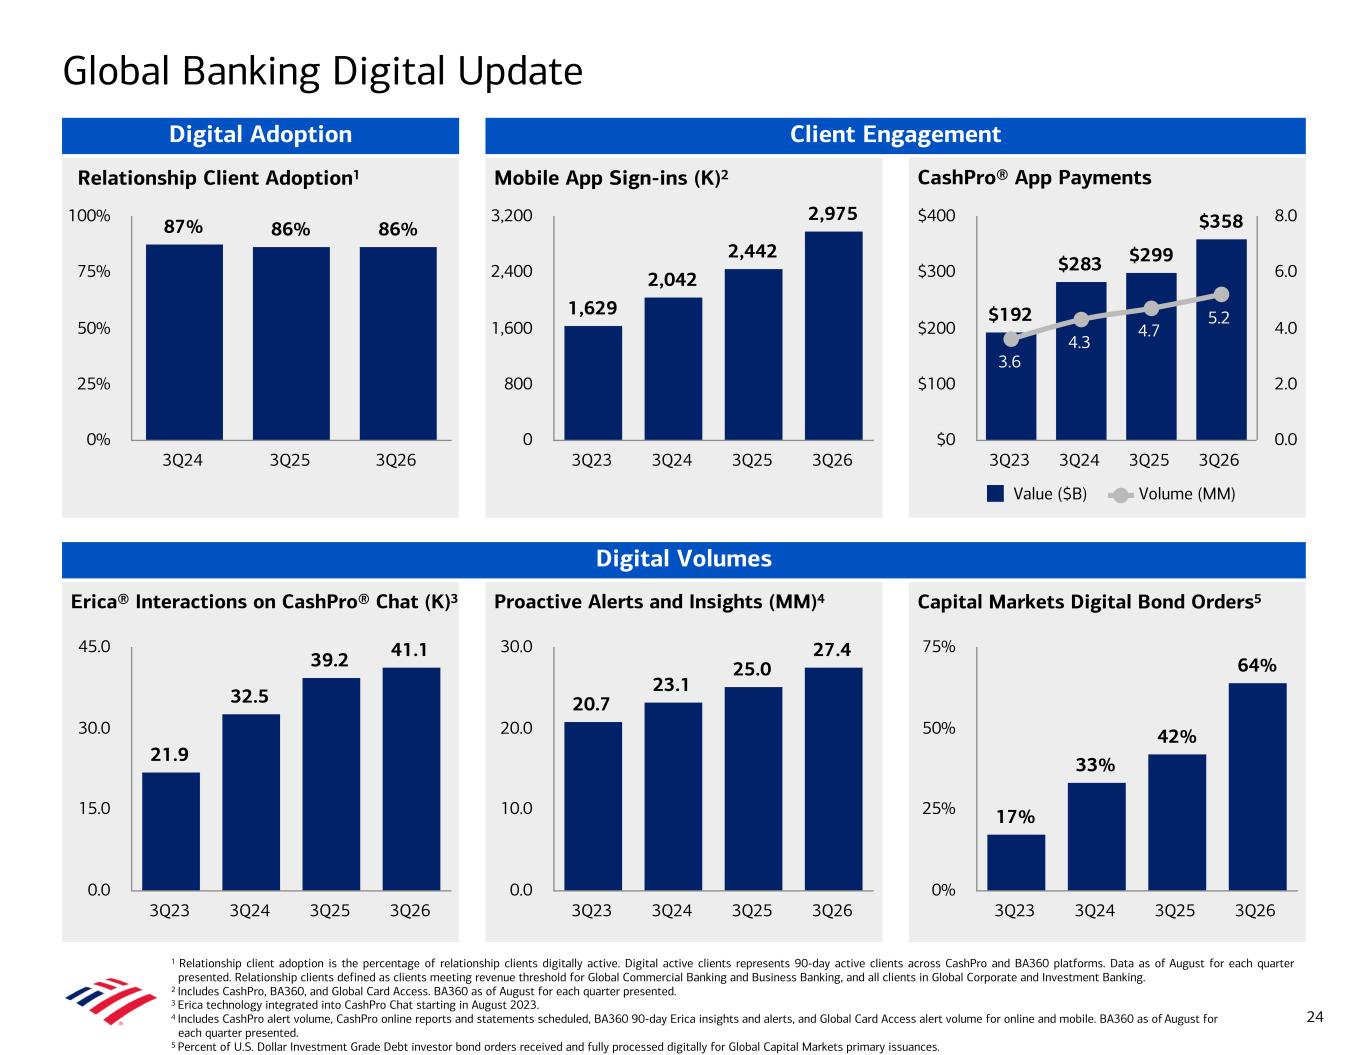
1 Relationship client adoption is the percentage of relationship clients digitally active. Digital active clients represents 90-day active clients across CashPro and BA360 platforms. Data as of August for each quarter presented. Relationship clients defined as clients meeting revenue threshold for Global Commercial Banking and Business Banking, and all clients in Global Corporate and Investment Banking. 2 Includes CashPro, BA360, and Global Card Access. BA360 as of August for each quarter presented. 3 Erica technology integrated into CashPro Chat starting in August 2023. 4 Includes CashPro alert volume, CashPro online reports and statements scheduled, BA360 90-day Erica insights and alerts, and Global Card Access alert volume for online and mobile. BA360 as of August for each quarter presented. 5 Percent of U.S. Dollar Investment Grade Debt investor bond orders received and fully processed digitally for Global Capital Markets primary issuances. Capital Markets Digital Bond Orders5 Erica® Interactions on CashPro® Chat (K)3 Proactive Alerts and Insights (MM)4 17% 33% 42% 64% 3Q23 3Q24 3Q25 3Q26 0% 25% 50% 75% 20.7 23.1 25.0 27.4 3Q23 3Q24 3Q25 3Q26 0.0 10.0 20.0 30.0 21.9 32.5 39.2 41.1 3Q23 3Q24 3Q25 3Q26 0.0 15.0 30.0 45.0 CashPro® App PaymentsRelationship Client Adoption1 Mobile App Sign-ins (K)2 $192 $283 $299 $358 3.6 4.3 4.7 5.2 Value ($B) Volume (MM) 3Q23 3Q24 3Q25 3Q26 $0 $100 $200 $300 $400 0.0 2.0 4.0 6.0 8.0 1,629 2,042 2,442 2,975 3Q23 3Q24 3Q25 3Q26 0 800 1,600 2,400 3,20087% 86% 86% 3Q24 3Q25 3Q26 0% 25% 50% 75% 100% Client Engagement Digital Volumes Global Banking Digital Update 24 Digital Adoption
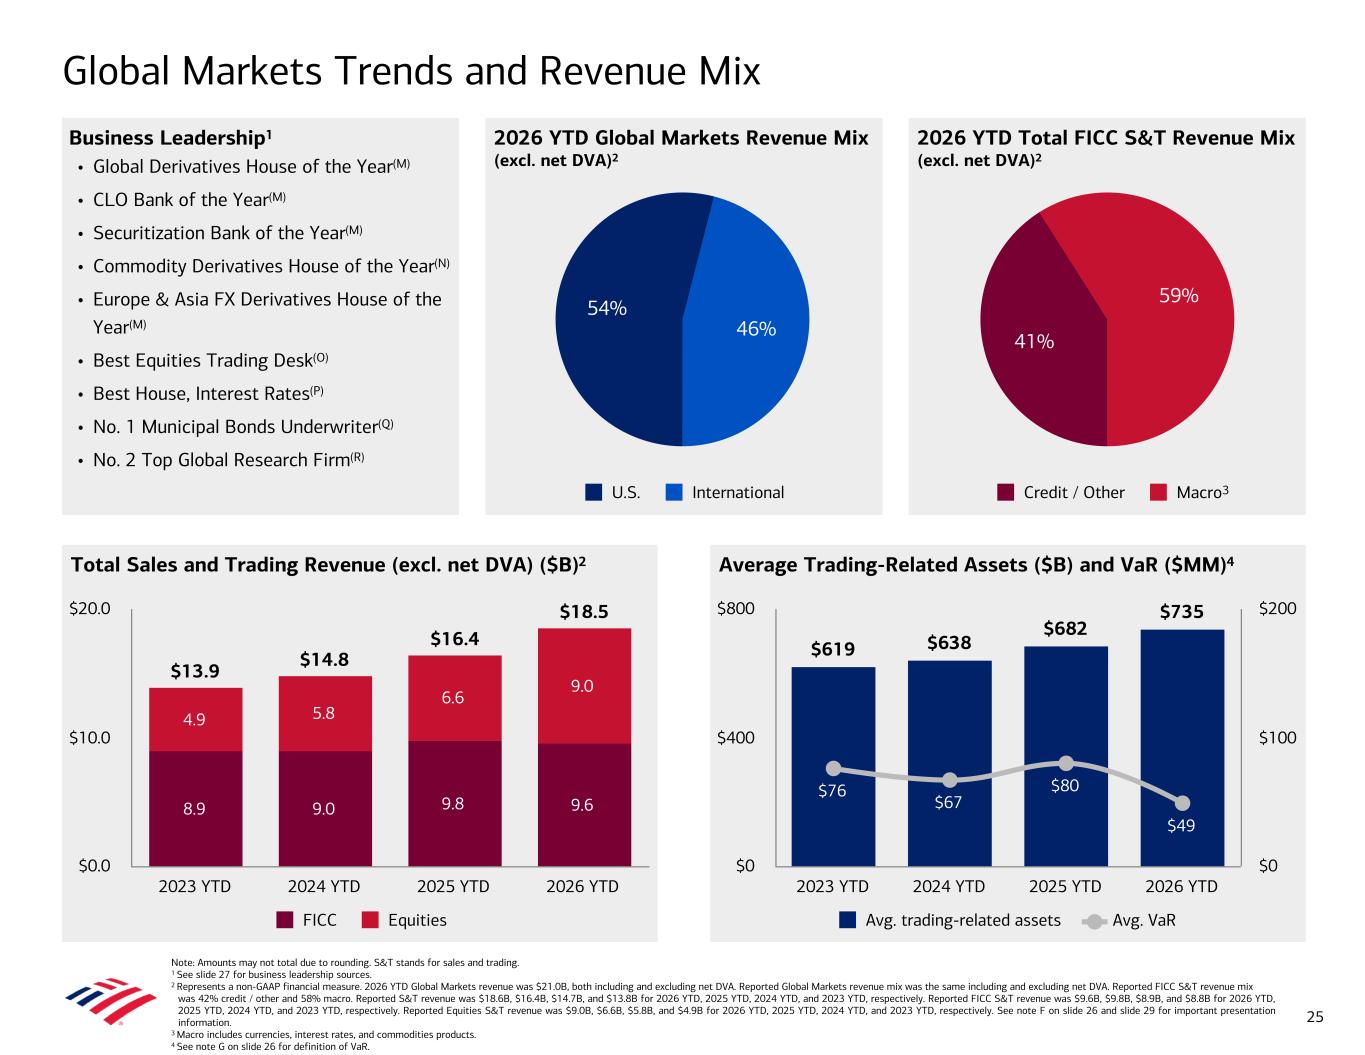
Note: Amounts may not total due to rounding. S&T stands for sales and trading. 1 See slide 27 for business leadership sources. 2 Represents a non-GAAP financial measure. 2026 YTD Global Markets revenue was $21.0B, both including and excluding net DVA. Reported Global Markets revenue mix was the same including and excluding net DVA. Reported FICC S&T revenue mix was 42% credit / other and 58% macro. Reported S&T revenue was $18.6B, $16.4B, $14.7B, and $13.8B for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. Reported FICC S&T revenue was $9.6B, $9.8B, $8.9B, and $8.8B for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. Reported Equities S&T revenue was $9.0B, $6.6B, $5.8B, and $4.9B for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. See note F on slide 26 and slide 29 for important presentation information. 3 Macro includes currencies, interest rates, and commodities products. 4 See note G on slide 26 for definition of VaR. Global Markets Trends and Revenue Mix 2026 YTD Global Markets Revenue Mix (excl. net DVA)2 Business Leadership1 • Global Derivatives House of the Year(M) • CLO Bank of the Year(M) • Securitization Bank of the Year(M) • Commodity Derivatives House of the Year(N) • Europe & Asia FX Derivatives House of the Year(M) • Best Equities Trading Desk(O) • Best House, Interest Rates(P) • No. 1 Municipal Bonds Underwriter(Q) • No. 2 Top Global Research Firm(R) 2026 YTD Total FICC S&T Revenue Mix (excl. net DVA)2 Total Sales and Trading Revenue (excl. net DVA) ($B)2 Average Trading-Related Assets ($B) and VaR ($MM)4 $13.9 $14.8 $16.4 $18.5 8.9 9.0 9.8 9.6 4.9 5.8 6.6 9.0 FICC Equities 2023 YTD 2024 YTD 2025 YTD 2026 YTD $0.0 $10.0 $20.0 $619 $638 $682 $735 $76 $67 $80 $49 Avg. trading-related assets Avg. VaR 2023 YTD 2024 YTD 2025 YTD 2026 YTD $0 $400 $800 $0 $100 $200 54% 46% U.S. International 41% 59% Credit / Other Macro 25 3
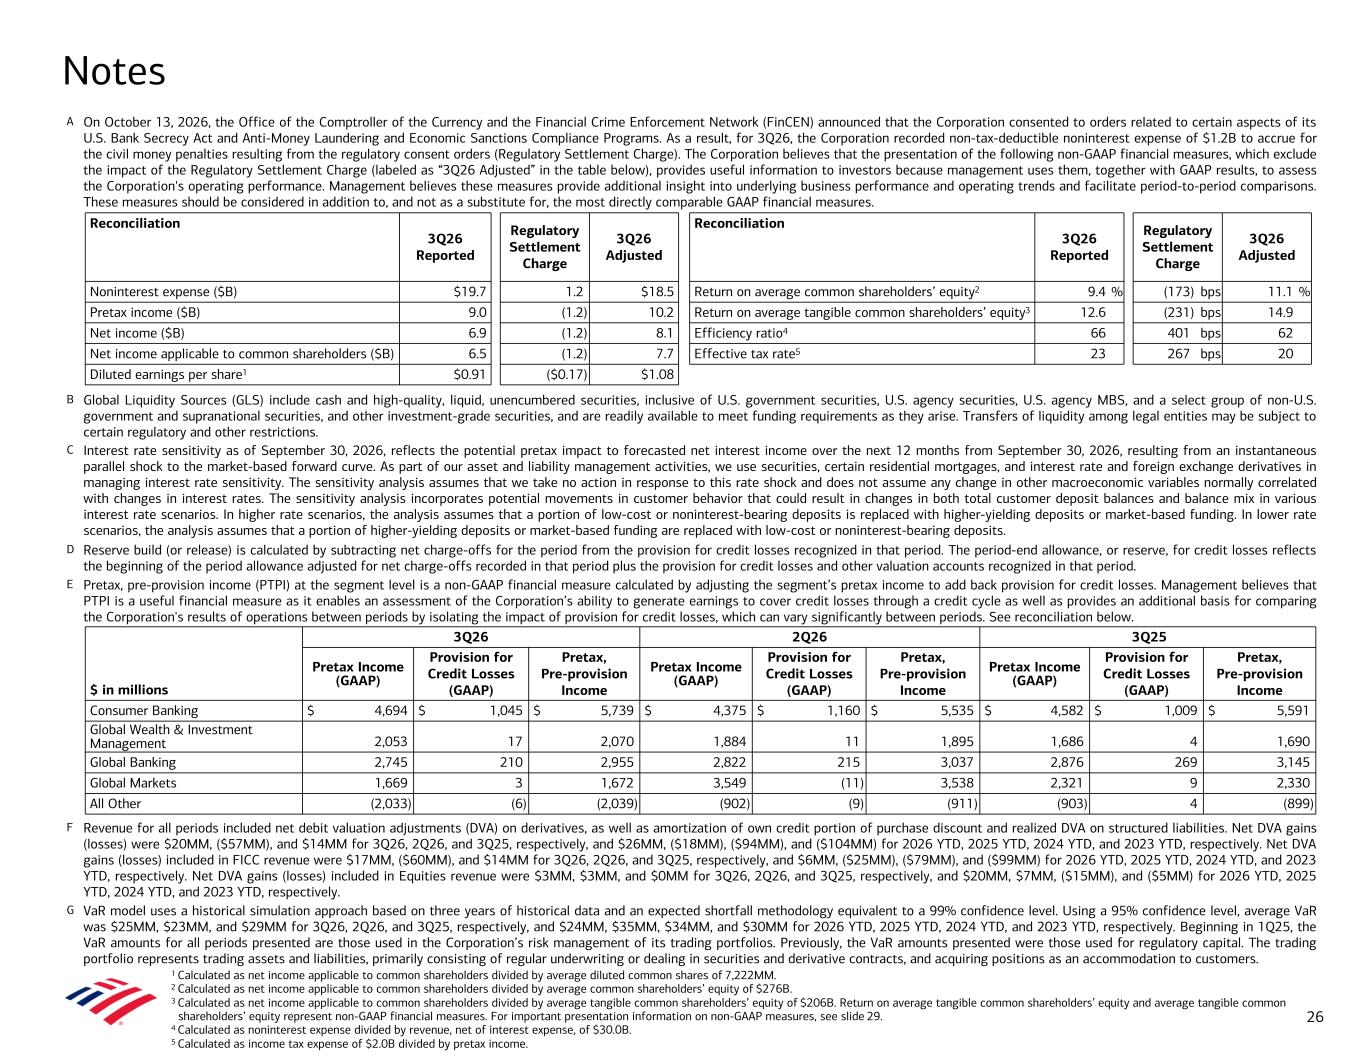
Notes 26 1 Calculated as net income applicable to common shareholders divided by average diluted common shares of 7,222MM. 2 Calculated as net income applicable to common shareholders divided by average common shareholders’ equity of $276B. 3 Calculated as net income applicable to common shareholders divided by average tangible common shareholders’ equity of $206B. Return on average tangible common shareholders’ equity and average tangible common shareholders’ equity represent non-GAAP financial measures. For important presentation information on non-GAAP measures, see slide 29. 4 Calculated as noninterest expense divided by revenue, net of interest expense, of $30.0B. 5 Calculated as income tax expense of $2.0B divided by pretax income. A On October 13, 2026, the Office of the Comptroller of the Currency and the Financial Crime Enforcement Network (FinCEN) announced that the Corporation consented to orders related to certain aspects of its U.S. Bank Secrecy Act and Anti-Money Laundering and Economic Sanctions Compliance Programs. As a result, for 3Q26, the Corporation recorded non-tax-deductible noninterest expense of $1.2B to accrue for the civil money penalties resulting from the regulatory consent orders (Regulatory Settlement Charge). The Corporation believes that the presentation of the following non-GAAP financial measures, which exclude the impact of the Regulatory Settlement Charge (labeled as “3Q26 Adjusted” in the table below), provides useful information to investors because management uses them, together with GAAP results, to assess the Corporation's operating performance. Management believes these measures provide additional insight into underlying business performance and operating trends and facilitate period-to-period comparisons. These measures should be considered in addition to, and not as a substitute for, the most directly comparable GAAP financial measures. B Global Liquidity Sources (GLS) include cash and high-quality, liquid, unencumbered securities, inclusive of U.S. government securities, U.S. agency securities, U.S. agency MBS, and a select group of non-U.S. government and supranational securities, and other investment-grade securities, and are readily available to meet funding requirements as they arise. Transfers of liquidity among legal entities may be subject to certain regulatory and other restrictions. C Interest rate sensitivity as of September 30, 2026, reflects the potential pretax impact to forecasted net interest income over the next 12 months from September 30, 2026, resulting from an instantaneous parallel shock to the market-based forward curve. As part of our asset and liability management activities, we use securities, certain residential mortgages, and interest rate and foreign exchange derivatives in managing interest rate sensitivity. The sensitivity analysis assumes that we take no action in response to this rate shock and does not assume any change in other macroeconomic variables normally correlated with changes in interest rates. The sensitivity analysis incorporates potential movements in customer behavior that could result in changes in both total customer deposit balances and balance mix in various interest rate scenarios. In higher rate scenarios, the analysis assumes that a portion of low-cost or noninterest-bearing deposits is replaced with higher-yielding deposits or market-based funding. In lower rate scenarios, the analysis assumes that a portion of higher-yielding deposits or market-based funding are replaced with low-cost or noninterest-bearing deposits. D Reserve build (or release) is calculated by subtracting net charge-offs for the period from the provision for credit losses recognized in that period. The period-end allowance, or reserve, for credit losses reflects the beginning of the period allowance adjusted for net charge-offs recorded in that period plus the provision for credit losses and other valuation accounts recognized in that period. E Pretax, pre-provision income (PTPI) at the segment level is a non-GAAP financial measure calculated by adjusting the segment’s pretax income to add back provision for credit losses. Management believes that PTPI is a useful financial measure as it enables an assessment of the Corporation’s ability to generate earnings to cover credit losses through a credit cycle as well as provides an additional basis for comparing the Corporation's results of operations between periods by isolating the impact of provision for credit losses, which can vary significantly between periods. See reconciliation below. F Revenue for all periods included net debit valuation adjustments (DVA) on derivatives, as well as amortization of own credit portion of purchase discount and realized DVA on structured liabilities. Net DVA gains (losses) were $20MM, ($57MM), and $14MM for 3Q26, 2Q26, and 3Q25, respectively, and $26MM, ($18MM), ($94MM), and ($104MM) for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. Net DVA gains (losses) included in FICC revenue were $17MM, ($60MM), and $14MM for 3Q26, 2Q26, and 3Q25, respectively, and $6MM, ($25MM), ($79MM), and ($99MM) for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. Net DVA gains (losses) included in Equities revenue were $3MM, $3MM, and $0MM for 3Q26, 2Q26, and 3Q25, respectively, and $20MM, $7MM, ($15MM), and ($5MM) for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. G VaR model uses a historical simulation approach based on three years of historical data and an expected shortfall methodology equivalent to a 99% confidence level. Using a 95% confidence level, average VaR was $25MM, $23MM, and $29MM for 3Q26, 2Q26, and 3Q25, respectively, and $24MM, $35MM, $34MM, and $30MM for 2026 YTD, 2025 YTD, 2024 YTD, and 2023 YTD, respectively. Beginning in 1Q25, the VaR amounts for all periods presented are those used in the Corporation’s risk management of its trading portfolios. Previously, the VaR amounts presented were those used for regulatory capital. The trading portfolio represents trading assets and liabilities, primarily consisting of regular underwriting or dealing in securities and derivative contracts, and acquiring positions as an accommodation to customers. $ in millions 3Q26 2Q26 3Q25 Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Consumer Banking $ 4,694 $ 1,045 $ 5,739 $ 4,375 $ 1,160 $ 5,535 $ 4,582 $ 1,009 $ 5,591 Global Wealth & Investment Management 2,053 17 2,070 1,884 11 1,895 1,686 4 1,690 Global Banking 2,745 210 2,955 2,822 215 3,037 2,876 269 3,145 Global Markets 1,669 3 1,672 3,549 (11) 3,538 2,321 9 2,330 All Other (2,033) (6) (2,039) (902) (9) (911) (903) 4 (899) Reconciliation 3Q26 Reported Regulatory Settlement Charge 3Q26 Adjusted Noninterest expense ($B) $19.7 1.2 $18.5 Pretax income ($B) 9.0 (1.2) 10.2 Net income ($B) 6.9 (1.2) 8.1 Net income applicable to common shareholders ($B) 6.5 (1.2) 7.7 Diluted earnings per share1 $0.91 ($0.17) $1.08 Reconciliation 3Q26 Reported Regulatory Settlement Charge 3Q26 Adjusted Return on average common shareholders’ equity2 9.4 % (173) bps 11.1 % Return on average tangible common shareholders’ equity3 12.6 (231) bps 14.9 Efficiency ratio4 66 401 bps 62 Effective tax rate5 23 267 bps 20
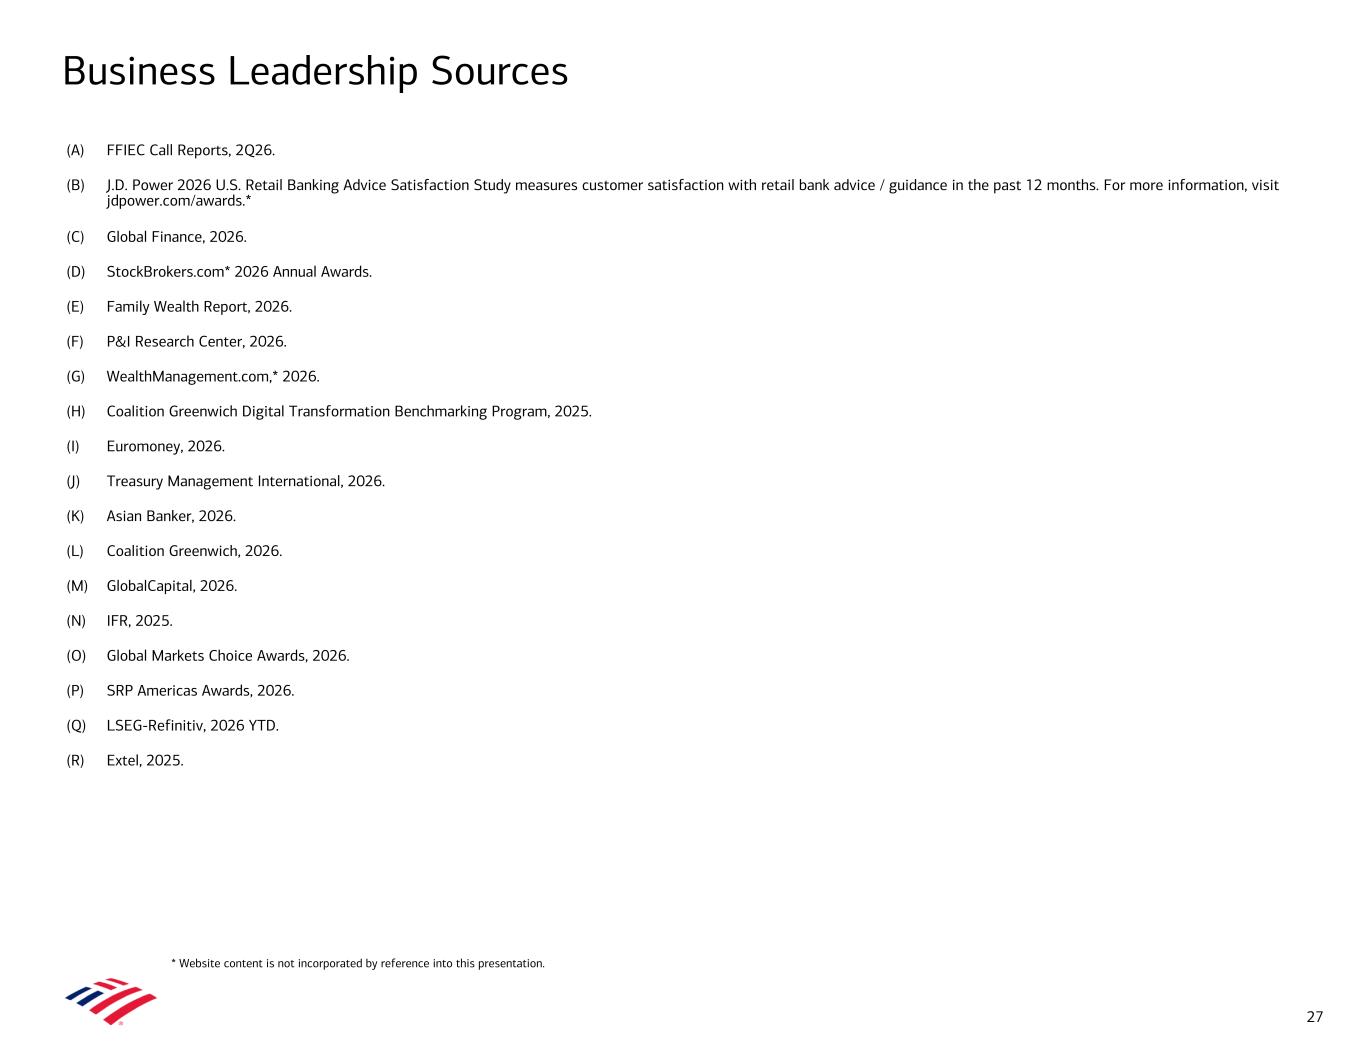
Business Leadership Sources (A) FFIEC Call Reports, 2Q26. (B) J.D. Power 2026 U.S. Retail Banking Advice Satisfaction Study measures customer satisfaction with retail bank advice / guidance in the past 12 months. For more information, visit jdpower.com/awards.* (C) Global Finance, 2026. (D) StockBrokers.com* 2026 Annual Awards. (E) Family Wealth Report, 2026. (F) P&I Research Center, 2026. (G) WealthManagement.com,* 2026. (H) Coalition Greenwich Digital Transformation Benchmarking Program, 2025. (I) Euromoney, 2026. (J) Treasury Management International, 2026. (K) Asian Banker, 2026. (L) Coalition Greenwich, 2026. (M) GlobalCapital, 2026. (N) IFR, 2025. (O) Global Markets Choice Awards, 2026. (P) SRP Americas Awards, 2026. (Q) LSEG-Refinitiv, 2026 YTD. (R) Extel, 2025. 27 * Website content is not incorporated by reference into this presentation.
Forward-Looking Statements Bank of America Corporation (the Corporation) and its management may make certain statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “intends,” “plans,” “goals,” “outlook,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements represent the Corporation’s current expectations, plans or forecasts of its or its business segments' future results, which may include, among other measures, revenue, liquidity, net interest income, net interest yield, other income, provision for credit losses, expenses, operating leverage, effective tax rate, efficiency ratio, capital measures, deposits and assets, as well as strategy, future business and economic conditions more generally, and other future matters. These statements are not guarantees of future results or performance and involve certain known and unknown risks, uncertainties and assumptions that are difficult to predict and are often beyond the Corporation’s control. Actual outcomes and results may differ materially from those expressed in, or implied by, any of these forward-looking statements. You should not place undue reliance on any forward-looking statement and should consider the following uncertainties and risks, as well as the risks and uncertainties more fully discussed under Item 1A. Risk Factors of the Corporation’s 2025 Annual Report on Form 10-K and in any of the Corporation’s subsequent U.S. Securities and Exchange Commission (SEC) filings: the Corporation’s potential judgments, orders, settlements, penalties, fines and reputational damage, which are inherently difficult to predict, including related to the adequacy of the Corporation's anti-money laundering and economic sanctions programs (including the consent orders associated therewith) and pending, threatened or future litigation and regulatory inquiries, demands, requests, investigations, proceedings and enforcement actions, which the Corporation is subject to in the ordinary course of business, including matters related to our processing of unemployment benefits for California and certain other states, the features of our automatic credit card payment service, and the processing of electronic payments, including through the Zelle network, and related fraud, which are in various stages; in connection with ongoing litigation, the impact of certain changes to Visa’s and Mastercard’s respective card payment network rules and reductions in interchange fees for U.S.-based merchants; the possibility that the Corporation's future liabilities may be in excess of its recorded liability and estimated range of possible loss for litigation, and regulatory and government actions; the impact of U.S. and global interest rates (including the potential for fluctuations in interest rates), inflation, currency exchange rates, economic conditions, trade policies and tensions, including changes in, or the imposition of, tariffs and / or trade barriers and the economic impacts, volatility and uncertainty resulting therefrom, which may have varying effects across industries and geographies, and geopolitical instability; uncertainties about the financial stability and growth rates of non-U.S. jurisdictions, the risk that those jurisdictions may face difficulties servicing their sovereign debt, and related stresses on financial markets, currencies and trade, and the Corporation’s exposures to such risks, including direct, indirect and operational; the impact of the interest rate, inflationary, macroeconomic, banking and regulatory environment on the Corporation’s assets, business, financial condition and results of operations; the impact of adverse developments affecting the U.S. or global banking industry, including a deterioration in private credit markets, bank failures and liquidity concerns, resulting in worsening economic and market volatility, and regulatory responses thereto; the possibility that future credit losses may be higher than currently expected, including due to changes in economic assumptions, which may include unemployment rates, real estate prices, gross domestic product levels and corporate bond spreads, customer behavior, adverse developments with respect to U.S. or global economic conditions and other uncertainties, such as the impact of trade policies, supply chain disruptions, commodity prices, inflationary pressures and labor shortages on economic conditions and our business; potential losses related to the Corporation’s concentration of credit risk; the Corporation's ability to achieve its expense targets (including noninterest expense) and expectations regarding revenue, net interest income, operating leverage, other income, provision for credit losses, net charge-offs, effective tax rate, loan or deposit growth or other projections and targets; variances to the underlying assumptions and judgments used in estimating banking book net interest income sensitivity; adverse changes to the Corporation’s credit ratings from the major credit rating agencies; an inability to access capital markets or maintain deposits or borrowing costs; estimates of the fair value and other accounting values, subject to impairment assessments, of certain of the Corporation’s assets and liabilities; the estimated or actual impact of changes in accounting standards or assumptions in applying those standards; uncertainty regarding the content, timing and impact of regulatory capital and liquidity requirements; the impact of adverse changes to total loss- absorbing capacity requirements, stress capital buffer requirements and / or global systemically important bank surcharges; the potential impact of actions of the Board of Governors of the Federal Reserve System on the Corporation’s capital plans; the effect of changes in or interpretations of income tax laws and regulations, including impacts from the 2025 Budget Reconciliation Act; the impact of implementation and compliance with U.S. and international laws, regulations and regulatory interpretations, including recovery and resolution planning requirements, Federal Deposit Insurance Corporation assessments, fiduciary standards, derivatives regulations and potential changes to loss allocations between financial institutions and customers, including for losses incurred from the use of our products and services, including electronic payments and payment of checks, that were authorized by the customer but induced by fraud; the impact of failures or disruptions in or breaches of the Corporation’s operations or information systems, or those of various third parties, including regulators and federal and state governments, such as from cybersecurity incidents; the risks related to the development, implementation, use and management of emerging technologies, including artificial intelligence and the ability to achieve expected or potential benefits, such as increased productivity, profitability and cost savings; the risks related to the transition and physical impacts of climate change; our ability to achieve environmental goals or the impact of any changes in the Corporation's sustainability or human capital management strategy or goals; the impact of uncertain or changing political conditions, federal government shutdowns, including partial shutdowns, and uncertainty regarding the federal government’s debt limit or changes in fiscal, monetary, trade or regulatory policy; the emergence of widespread health emergencies or pandemics; the impact of natural disasters, extreme weather events, military conflicts (including the Russia / Ukraine conflict, the conflicts in the Middle East, the possible expansion of such conflicts and potential geopolitical and economic consequences), civil unrest, terrorism or other geopolitical events; and other matters. Forward-looking statements speak only as of the date they are made, and the Corporation undertakes no obligation to update any forward-looking statement to reflect the impact of circumstances or events that arise after the date the forward-looking statement was made. 28
Important Presentation Information 29 • The information contained herein is preliminary and based on Corporation data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying slides. Bank of America does not undertake an obligation to, and disclaims any duty to, update any of the information provided. • The Corporation may present certain metrics and ratios, including year-over-year comparisons of revenue, noninterest expense, and pretax income, excluding certain items (e.g., DVA), and ratios utilizing tangible common equity and tangible assets, that are non-GAAP financial measures. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. For more information about the non-GAAP financial measures contained herein, please see the presentation of the most directly comparable financial measures calculated in accordance with GAAP and accompanying reconciliations in the earnings press release for the quarter ended September 30, 2026, and other earnings-related information available through the Bank of America Investor Relations website at: https://investor.bankofamerica.com/ quarterly-earnings, the content of which is not incorporated by reference into this presentation. The Corporation has not provided a reconciliation of forward-looking estimates of net interest income on an FTE basis (as defined below) to the most directly comparable GAAP measure as it cannot be prepared without unreasonable effort. • The Corporation also measures net interest income, revenue, and certain ratios and analyses on a fully taxable-equivalent (FTE) basis, which when presented on a consolidated basis are non-GAAP financial measures. The Corporation believes managing the business with net interest income on an FTE basis provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that the presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practices. The FTE adjustments were $161MM, $163MM, $162MM, $165MM, and $154MM for 3Q26, 2Q26, 1Q26, 4Q25, and 3Q25, respectively. • The Corporation presents certain key financial and nonfinancial performance indicators (KPIs) that management uses when assessing consolidated and / or segment results. The Corporation believes this information is useful because it provides management and investors with information about underlying operational performance and trends. KPIs are presented herein, including in the 3Q26 Highlights on slides 2 and 5 and on Summary Income Statement for each segment. • The Corporation allocates capital to its business segments using a methodology that considers the effect of regulatory capital requirements in addition to internal risk-based capital models. Allocated capital is reviewed periodically and refinements are made based on multiple considerations that include, but are not limited to, risk-weighted assets measured under Basel 3 Standardized and Advanced approaches, business segment exposures and risk profile, and strategic plans. As a result of this process, in 1Q26, the Corporation adjusted the amount of capital being allocated to its business segments.